

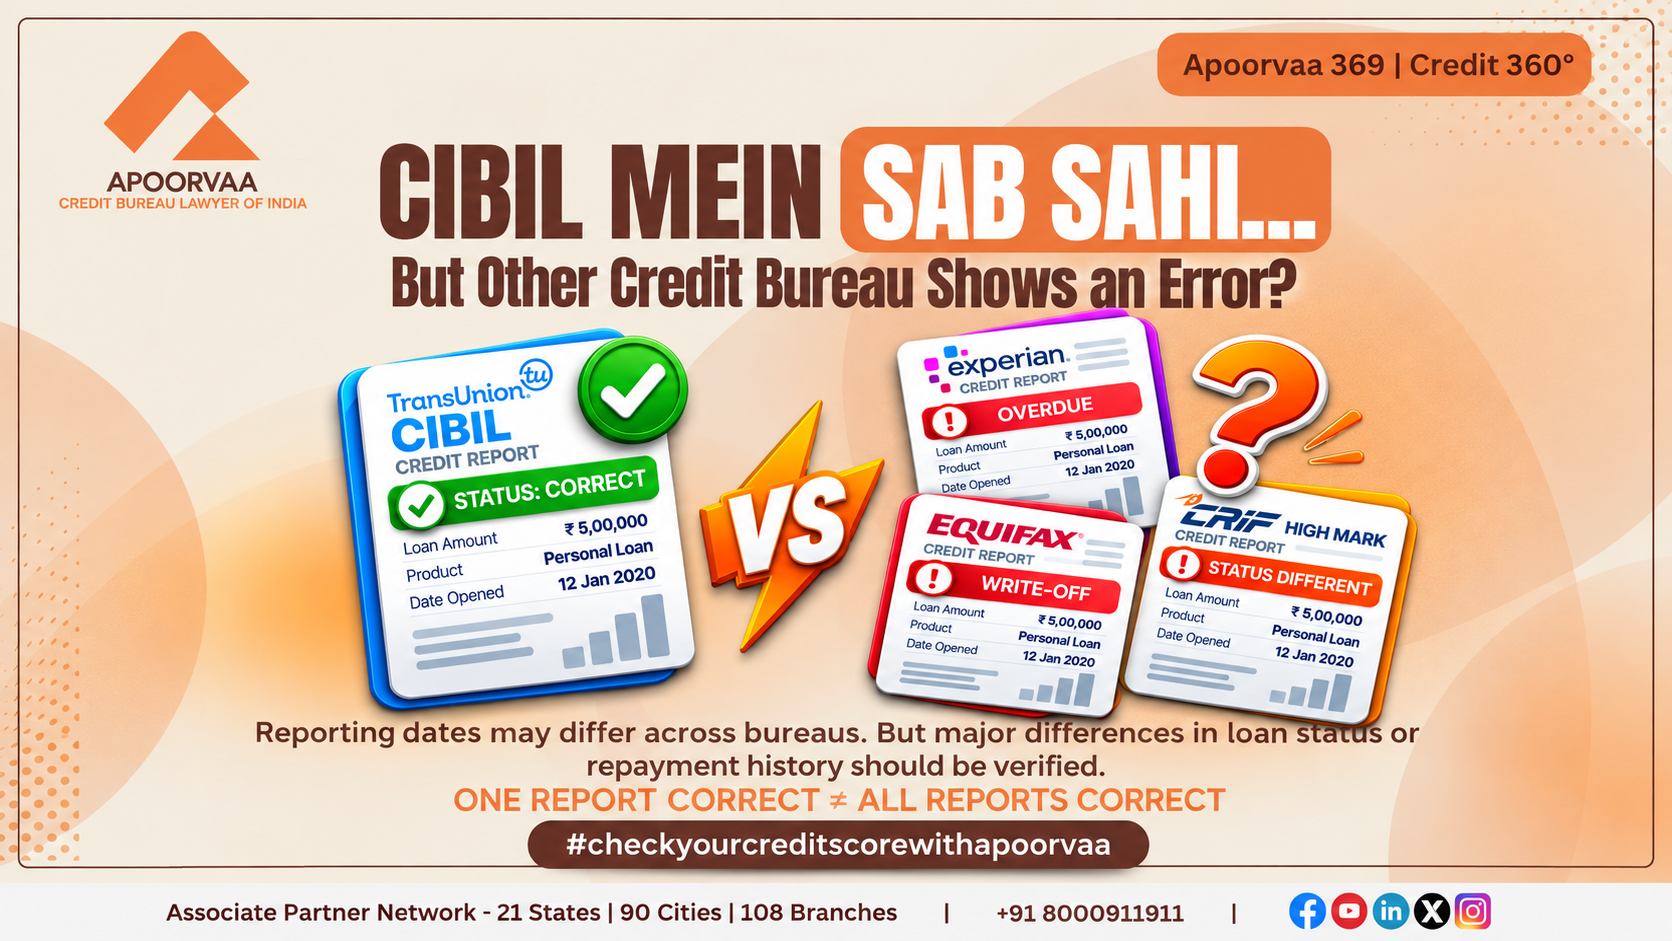
“My CIBIL Report is correct, but Experian, Equifax or CRIF High Mark is showing different information for the same loan. Does that mean the other Credit Report is wrong?”
This is an important credit-reporting issue—and it should not be confused with simply having different credit scores across bureaus.
India has four Credit Information Companies: TransUnion CIBIL, Experian, Equifax and CRIF High Mark. A borrower may therefore have credit information maintained across multiple CICs.
Sometimes the same loan may not look identical in every report at a particular point in time.
For example:
CIBIL: Closed
Another bureau: Current Balance still showing
Or:
CIBIL: No overdue
Another bureau: Overdue amount reflected
Or one bureau may show an updated account while another continues to reflect older information.
Does every such difference mean there is an error?
No. But a material inconsistency in the same identifiable account should not simply be ignored either.
The first task is to establish whether the difference is caused by the reporting/update position or whether the underlying credit information itself is inconsistent.
Different Score vs Different Account Data: They Are Not the Same Problem
Suppose your CIBIL Score and Experian Score are different.
That alone does not establish an error.
Credit scores are generated by the respective Credit Information Companies, and differences in scoring methodology and the information available at the relevant point can result in different scores.
But consider another situation.
The same personal loan shows:
CIBIL: Closed with ₹0 Current Balance
while:
Experian: Active with Current Balance still outstanding.
That is not simply a score difference.
Similarly:
CIBIL: No overdue
while:
Equifax: Material overdue showing
is a question about the underlying account data.
This distinction is critical.
Different scores may be normal. Materially different facts about the same credit account require verification.
Why Can the Same Loan Look Different Across Credit Bureaus?
One possible reason is the reporting and update position.
Credit information is furnished by Credit Institutions to Credit Information Companies under RBI’s regulatory framework.
Under the current reporting framework effective from 1 July 2026, credit information is required to be reported using reference dates of the 9th, 16th, 23rd and last day of the month, or at shorter mutually agreed intervals, subject to the applicable submission timelines.
Therefore, the old assumption that credit information is simply “updated once a month” is no longer an accurate description of the current framework.
Even with more frequent reporting, however, reports obtained at a particular moment may not necessarily display every account field in an identical state.
A recent payment, loan closure or account update may already be reflected in one report while another report still reflects an earlier data position.
That can potentially explain some differences.
But reporting timing should not become a blanket explanation for every inconsistency.
What If CIBIL Shows Closed but Another Bureau Shows Outstanding?
Suppose you recently closed a loan.
Your CIBIL Report shows:
Status: Closed
Current Balance: ₹0
But another bureau still reflects a Current Balance.
Before concluding that the second report is incorrect, examine the relevant dates.
If that report is reflecting an earlier data position, the difference may be connected with timing.
But if the lender’s verified records establish that the loan is closed and materially outdated information continues to be reflected despite subsequent reporting, the issue may require further examination.
So the correct approach is not:
“CIBIL is correct, therefore the other bureau must be wrong.”
It is:
“What is the accurate account position, and what reporting period does each report represent?”
What If One Bureau Shows Write-Off or Overdue but CIBIL Does Not?
This deserves closer attention.
Imagine the same identifiable account shows:
CIBIL: No overdue / normal account status
while another bureau reflects:
Overdue, Write-Off or another materially adverse status.
This should not automatically be dismissed as a normal difference between credit bureaus.
At the same time, we should not automatically declare the adverse information incorrect merely because CIBIL does not show it.
The relevant questions are:
- Are we definitely comparing the same account?
- Are the reports reflecting comparable reporting periods?
- What does the lender’s underlying account history establish?
- Is one report carrying older information?
- Or is there a genuine inconsistency requiring rectification?
The objective is to determine which information is accurate.
Account Missing vs Account Showing Different Information
There is another distinction consumers should understand.
If a loan appears in CIBIL but is completely absent from another bureau report, that is a missing-account question.
But if the same loan appears in both reports and one shows Closed while another shows Active, or one shows no overdue while another shows a material overdue, that is a data-consistency question.
These situations should not be treated as the same problem.
And an account being absent from one report does not automatically prove that the information appearing in another report is incorrect.
When Does a Cross-Bureau Difference Require Serious Attention?
Not every small or temporary difference requires the same level of concern.
But closer examination becomes important when the same identifiable credit account shows materially conflicting information relating to areas such as:
- Current Balance
- Amount Overdue
- Account status
- Closure
- Repayment history
- Ownership or account attribution
RBI’s framework requires Credit Institutions to take steps to ensure that credit information furnished by them is updated, accurate and complete.
Therefore, if materially conflicting information continues to appear, the correct response is not simply:
“There are four bureaus, so differences are normal.”
The underlying account information should be verified.
That is where the distinction between a temporary reporting difference and a genuine Credit Report discrepancy becomes important.
How Can You Tell Whether It Is a Reporting Delay or a Genuine Discrepancy?
The most important factor is context.
If a loan was recently closed, paid or updated, and one bureau reflects an earlier reporting position, the difference may be temporary.
But suppose the reports are reflecting comparable periods and the same identifiable account continues to show materially different information.
For example:
One bureau: No overdue
Another bureau: Significant overdue
or:
One bureau: Normal account status
Another bureau: Materially adverse status
In such situations, the difference deserves closer examination.
A useful principle is:
A recent timing difference may explain older information. It should not automatically explain materially conflicting account information.
The actual lender records and relevant reporting position should establish which information is accurate.
What Is the Lender’s Role When Credit Bureau Data Conflicts?
Credit Information Companies do not originate the loan.
The relevant Credit Institution furnishes account information into the regulated credit-information ecosystem.
RBI requires Credit Institutions to take necessary steps to ensure that the credit information furnished by them is updated, accurate and complete.
Therefore, where materially different information appears for the same account, an important question is:
What is the lender’s verified account position, and what information was furnished for the relevant reporting period?
This becomes particularly important when the discrepancy concerns Current Balance, overdue, closure, account status or repayment history.
What Is the Role of CIBIL, Experian, Equifax or CRIF High Mark?
Each Credit Information Company maintains credit information received within the applicable credit-reporting framework and provides mechanisms for consumers to raise disputes regarding information appearing in their reports.
However, where disputed account information originates from a Credit Institution, the relevant lender’s verification can be necessary before lender-furnished information is modified.
This is why Credit Rectification should not simply mean:
“CIBIL looks correct, so make every other bureau exactly the same.”
First establish which information is factually accurate.
Then determine whether a particular report requires rectification.
One Correct CIBIL Report Does Not Automatically Mean the Other Reports Are Correct
Many borrowers use “CIBIL” as a general term for their complete credit profile.
But TransUnion CIBIL is one of India’s four Credit Information Companies.
If your CIBIL Report accurately reflects an account, that is important.
However, it does not by itself establish that Experian, Equifax and CRIF High Mark are reflecting the same account accurately.
Likewise, if another bureau shows information different from CIBIL, CIBIL should not automatically be treated as correct simply because its information is more favourable.
Accuracy must come from the underlying credit relationship and verified account information—not from the name of the bureau.
When Does Professional Four-Bureau Analysis Become Relevant?
A professional four-bureau review can become particularly relevant when the same identifiable account shows a material inconsistency, such as:
- Closed in one report but outstanding in another
- No overdue in one report but significant overdue in another
- Updated information in one report but materially older information continuing elsewhere
- Normal account status in one report but materially different adverse status in another
- Repayment history that requires reconciliation with the lender’s records
- An account or ownership relationship that cannot be properly established
The purpose is not to manufacture disputes across four bureaus.
The purpose is to determine what the correct account position is and whether any information genuinely requires Credit Rectification.
Frequently Asked Questions
1. Why is my CIBIL Report correct but Experian, Equifax or CRIF High Mark is different?
The reports may reflect different reporting/update positions, or there may be an underlying account-data discrepancy. The same account and relevant reporting dates should be compared before reaching a conclusion.
2. Can my credit scores be different across all four bureaus?
Yes. Different credit scores do not automatically mean that the underlying account information is incorrect.
3. CIBIL shows Closed but another bureau shows outstanding. Is it an error?
Not automatically. If the other report reflects an earlier data position, timing may explain it. If materially outdated information continues despite the verified updated account position, further examination may be required.
4. What if one bureau shows Write-Off or overdue but CIBIL does not?
A materially different adverse status should be verified against the lender’s account records and relevant reporting period. It should neither be ignored nor automatically assumed to be incorrect.
5. Should all four reports be made identical?
The objective is not cosmetic uniformity. The objective is accurate credit information. Where the same facts should be represented, material inconsistencies need to be understood and, where appropriate, rectified.
6. Should I check all four reports if I find a major discrepancy?
Where a material inconsistency has already been identified, reviewing the relevant information across all four bureaus can help establish whether the issue is isolated or affects the broader credit profile.
My Perspective
A borrower often tells us:
“My CIBIL is completely correct, so why is another bureau showing something different?”
The answer should not simply be:
“Every bureau is different.”
Yes, credit scores can differ.
Yes, reporting and update positions can sometimes create temporary differences.
But when the same identifiable loan shows materially conflicting balance, overdue, repayment history or account status, we need to understand why.
The purpose of four-bureau analysis is not to decide which bureau gives the best-looking report.
It is to establish which information accurately represents the borrower’s actual credit relationship.
That is the foundation of meaningful Credit Rectification.
Final Takeaway
If CIBIL is correct but Experian, Equifax or CRIF High Mark shows different information, first distinguish:
Different Credit Score
from
Different Underlying Account Data
Then determine whether the difference can reasonably be explained by reporting/update timing or whether the same account contains a material inconsistency requiring further examination.
One correct bureau report does not automatically validate every other report—and one different report does not automatically mean it is wrong.
Accuracy must be established first.
Professional Four-Bureau Credit Report Assessment & Rectification
If the same loan shows materially different Current Balance, overdue, account status, repayment history or other information across your credit reports, Apoorvaa provides professional four-bureau Credit Report assessment and Credit Rectification for individuals and businesses.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported information, an increase in any credit score or future loan approval.
Related Credit Education
- Loan Is Yours but Lender Name Is Different in CIBIL Report? Here’s Why
- Four Credit Bureaus in India: Is Correcting Only CIBIL Enough?
- Why Is Your Credit Score Different Across CIBIL, Experian, Equifax and CRIF High Mark?
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed