

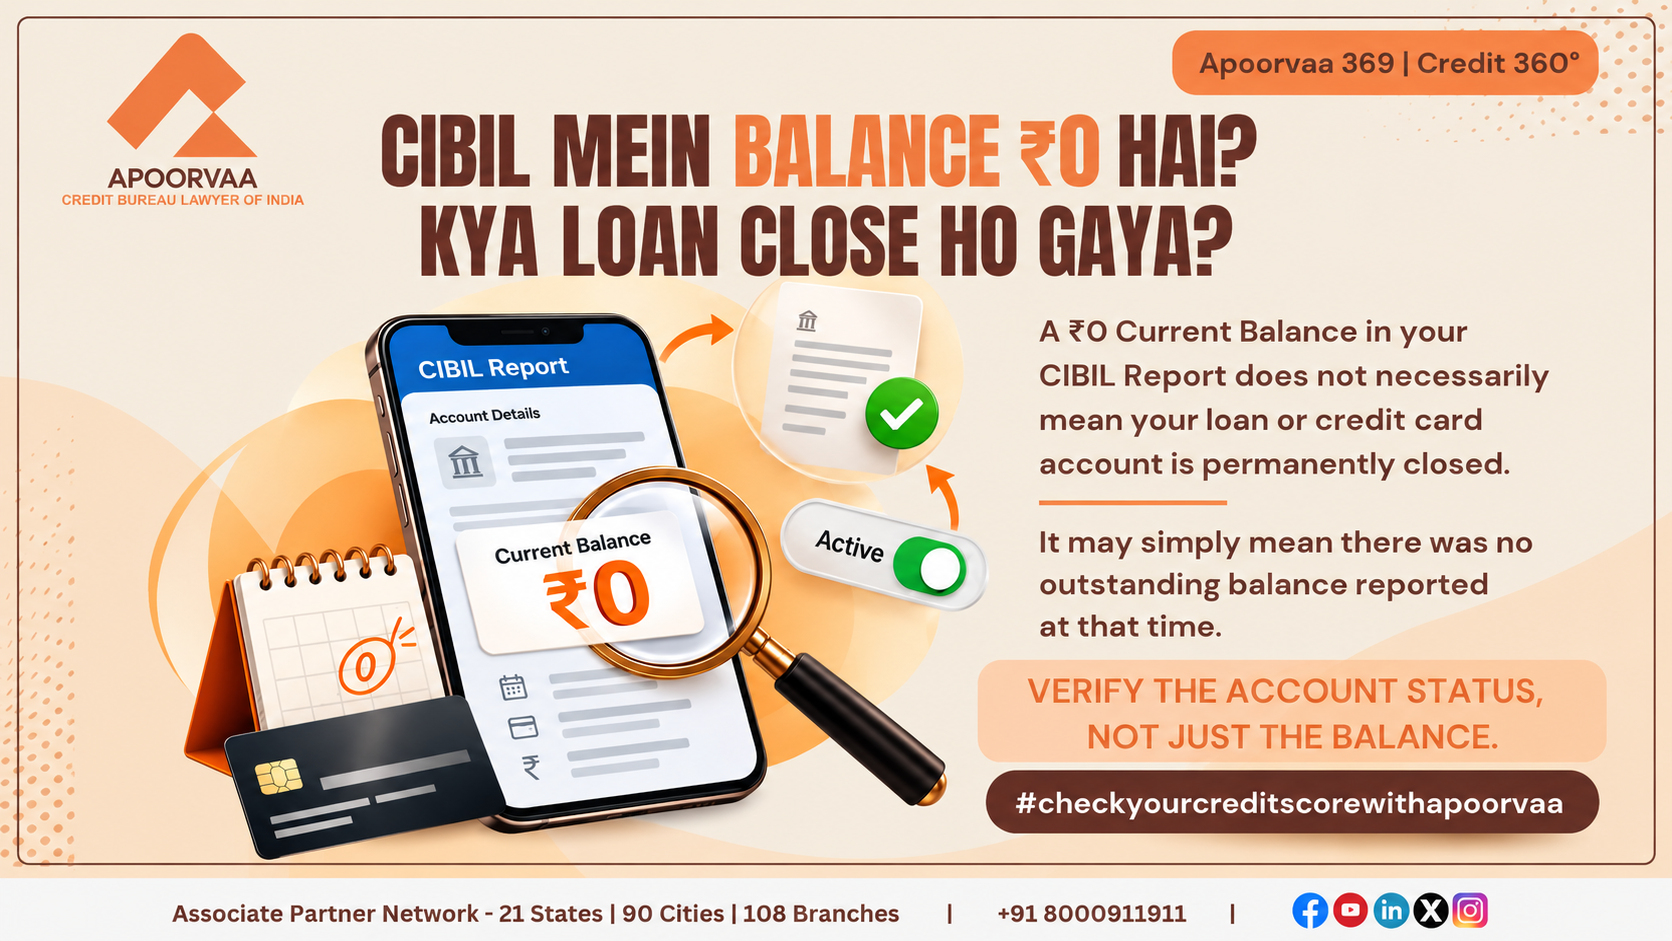
“My CIBIL Report shows ₹0 Current Balance. Does that mean my credit card is closed?”
Many consumers assume that once their credit-card outstanding balance becomes zero, the account is automatically closed. However, a zero balance and permanent credit-card closure are two different things.
A credit card may show no outstanding balance in the CIBIL Report while remaining active, with its credit limit still available for future transactions.
Understanding this difference is important because an unused but active card may still attract applicable charges under its terms.
1. What Does Current Balance ₹0 Mean in a CIBIL Report?
According to TransUnion CIBIL, the Account Information section of a credit report contains details such as Current Balance, Amount Overdue, Credit Limit and repayment history.
Current Balance refers to the outstanding balance reported by the credit institution for the account.
When a report shows Current Balance: ₹0, it generally means no outstanding amount was reported under that field as of the relevant reporting date.
It does not independently confirm that the account has been permanently closed.
For example, a consumer may have a credit card with a ₹1,00,000 limit and clear the entire outstanding balance.
The report may subsequently show ₹0, while the card remains active and available for future use.
₹0 Current Balance ≠ Account Closed
Another important consideration is reporting time. A CIBIL Report reflects information furnished by the lender as of a particular date. Transactions or charges arising afterwards may not yet appear.
2. Zero Balance vs Closed Credit Card: What’s the Difference?
A zero balance describes the account’s reported financial position.
Formal closure means the credit-card facility has been terminated by the issuer.
| Credit-report field | What it indicates |
| Current Balance | Reported outstanding balance |
| Amount Overdue | Amount reported as overdue |
| Credit Limit | Sanctioned credit-card limit |
| Account Status | Relevant account classification or status |
| Date Closed | Reported closure date, where applicable |
A card may have a ₹0 Current Balance and ₹0 Amount Overdue while remaining active.
Similarly, a closed credit card may continue to appear in the report as historical credit information.
Therefore, the Current Balance alone cannot establish whether a credit-card account is active or closed.
3. Can an Unused Credit Card Still Attract Annual Fees?
Yes, depending on the card’s terms.
Stopping card usage does not automatically terminate the credit-card agreement.
An active credit card may attract annual or renewal fees where such charges are applicable and have not been waived.
For example, a consumer may clear all outstanding dues and stop using a card. If the account remains active, an applicable renewal fee may subsequently become payable.
If a valid charge remains unpaid, it may create an outstanding obligation and potentially affect future credit reporting.
However, not every unused card attracts annual fees. Some cards are lifetime-free, while others offer conditional fee waivers.
The important point is that non-use should not be confused with permanent closure.
4. What Does RBI Say About Credit-Card Closure?
The Reserve Bank of India’s Credit Card and Debit Card – Issuance and Conduct Directions, 2022, as amended, prescribe requirements for credit-card closure.
Seven-Working-Day Rule
Under paragraph 8(a), a card issuer must honour a credit-card closure request within seven working days, subject to payment of all dues.
Issuers must provide multiple channels for closure requests, including suitable digital and customer-service channels.
Once the account is closed, the issuer must notify the cardholder immediately through the prescribed communication channels.
Where closure is delayed beyond the permitted period, RBI provides for a penalty of ₹500 per calendar day of qualifying delay, provided there is no outstanding amount and the applicable conditions are satisfied.
This makes it important to distinguish between submitting a closure request and receiving confirmation that closure has actually been completed.
5. What Happens When a Credit Card Is Unused for More Than One Year?
RBI also addresses credit cards that have not been used for more than one year.
Under paragraph 8(b), the issuer must initiate the closure process after intimating the cardholder.
If the cardholder does not respond within 30 days, the issuer must close the account, subject to payment of all dues, and update the relevant Credit Information Companies within the prescribed period.
This does not mean every card automatically closes exactly one year after its last transaction.
The prescribed notification and closure process remains relevant.
Consumers should also understand that blocking, deactivating and permanently closing a credit card are not necessarily the same thing.
A blocked card may be unusable while the underlying credit-card account remains open.
6. Why Are Closure Confirmation and Reporting Accuracy Important?
A closure request establishes the consumer’s intention to close the account.
A service-request number or acknowledgement helps document that the request was received.
However, neither necessarily proves that closure has been completed.
The issuer’s final closure confirmation is important evidence of the account’s actual position.
Even after formal closure, the account may remain visible in CIBIL as part of the consumer’s historical credit information.
A closed credit card appearing in CIBIL is not automatically a reporting error.
The relevant question is whether the report accurately reflects the completed closure.
If the issuer confirms that the account is closed but the credit report continues to inaccurately show it as active, the closure date, reporting date and account records may require examination.
A recent closure may not immediately appear in the report because credit information is updated through reporting cycles.
However, a genuine discrepancy that remains after the applicable reporting requirements may justify Credit Rectification.
7. When Is Professional Credit Rectification Required?
Professional Credit Rectification may be appropriate where the underlying account information is inaccurate.
Examples include:
- A formally closed credit card incorrectly reported as active.
- An inaccurate outstanding balance after confirmed settlement of dues.
- Incorrect account ownership or closure information.
However, rectification is not automatically required merely because the Current Balance is ₹0 or a closed account remains visible as historical information.
The objective is to correct genuine reporting inaccuracies, not remove accurate credit history.
Frequently Asked Questions
Does ₹0 Current Balance mean my credit card is closed?
No. It indicates the reported balance, not necessarily the account’s closure status.
Can an active credit card show ₹0 balance?
Yes. An active card may have no outstanding balance while retaining an available credit limit.
Does RBI require banks to close credit cards within seven working days?
Yes, subject to payment of all dues and the applicable closure requirements.
Will my closed credit card disappear from CIBIL?
Not necessarily. Accurate historical account information may remain visible after closure.
What if my bank confirms closure but CIBIL still shows the card as active?
The closure confirmation and reporting records should be examined. If the information is genuinely inaccurate, Credit Rectification may be justified.
My Perspective
In my professional experience, consumers often confuse repayment of outstanding dues with permanent termination of a credit facility.
A borrower may believe that because the credit-card balance is zero, there is nothing further to verify.
But an active credit card and a closed credit-card account have different implications.
I believe consumers should distinguish three things:
Payment of Dues. Formal Account Closure. Accurate Credit-Bureau Reporting.
Each must be understood separately.
Where the lender has completed closure, the credit information should accurately reflect that position. Where the card remains active, a zero balance alone should not create the impression that the facility has been terminated.
Final Takeaway
A CIBIL Current Balance of ₹0 does not automatically mean your credit card is permanently closed.
An active card may have no reported outstanding amount, retain an available credit limit and remain subject to applicable charges.
RBI prescribes formal closure requirements, while accurate credit-bureau reporting remains essential after closure.
₹0 BALANCE ≠ ACCOUNT CLOSED
VERIFY THE ACCOUNT STATUS, NOT JUST THE BALANCE.
Need Professional Credit Report Analysis?
If your credit-card issuer has confirmed closure but your CIBIL Report contains inaccurate account information, Apoorvaa can assist with professional Credit Report analysis and evaluation of genuine Credit Rectification requirements.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification addresses genuine reporting inaccuracies. It does not guarantee deletion of accurate account history or a particular credit-score outcome.
Related Credit Education
- NH or NA in CIBIL Score: Can You Still Get a Loan?
- Loan Closed but CIBIL Shows Outstanding Balance? Here’s Why
- EMI Never Paid Late but CIBIL Shows DPD? What Should You Check?
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed