

“I checked my CIBIL Report, but instead of a numerical score, it shows NH or NA. Does this mean the bank will reject my loan application?”
This is a common concern among borrowers who are new to credit, have limited recent credit activity or do not have sufficient information available for a numerical CIBIL Score.
Many consumers assume that if their report does not display a score between 300 and 900, something must be wrong with their credit profile.
Some even believe that NH or NA is a negative remark indicating overdue payments, default or poor repayment behaviour.
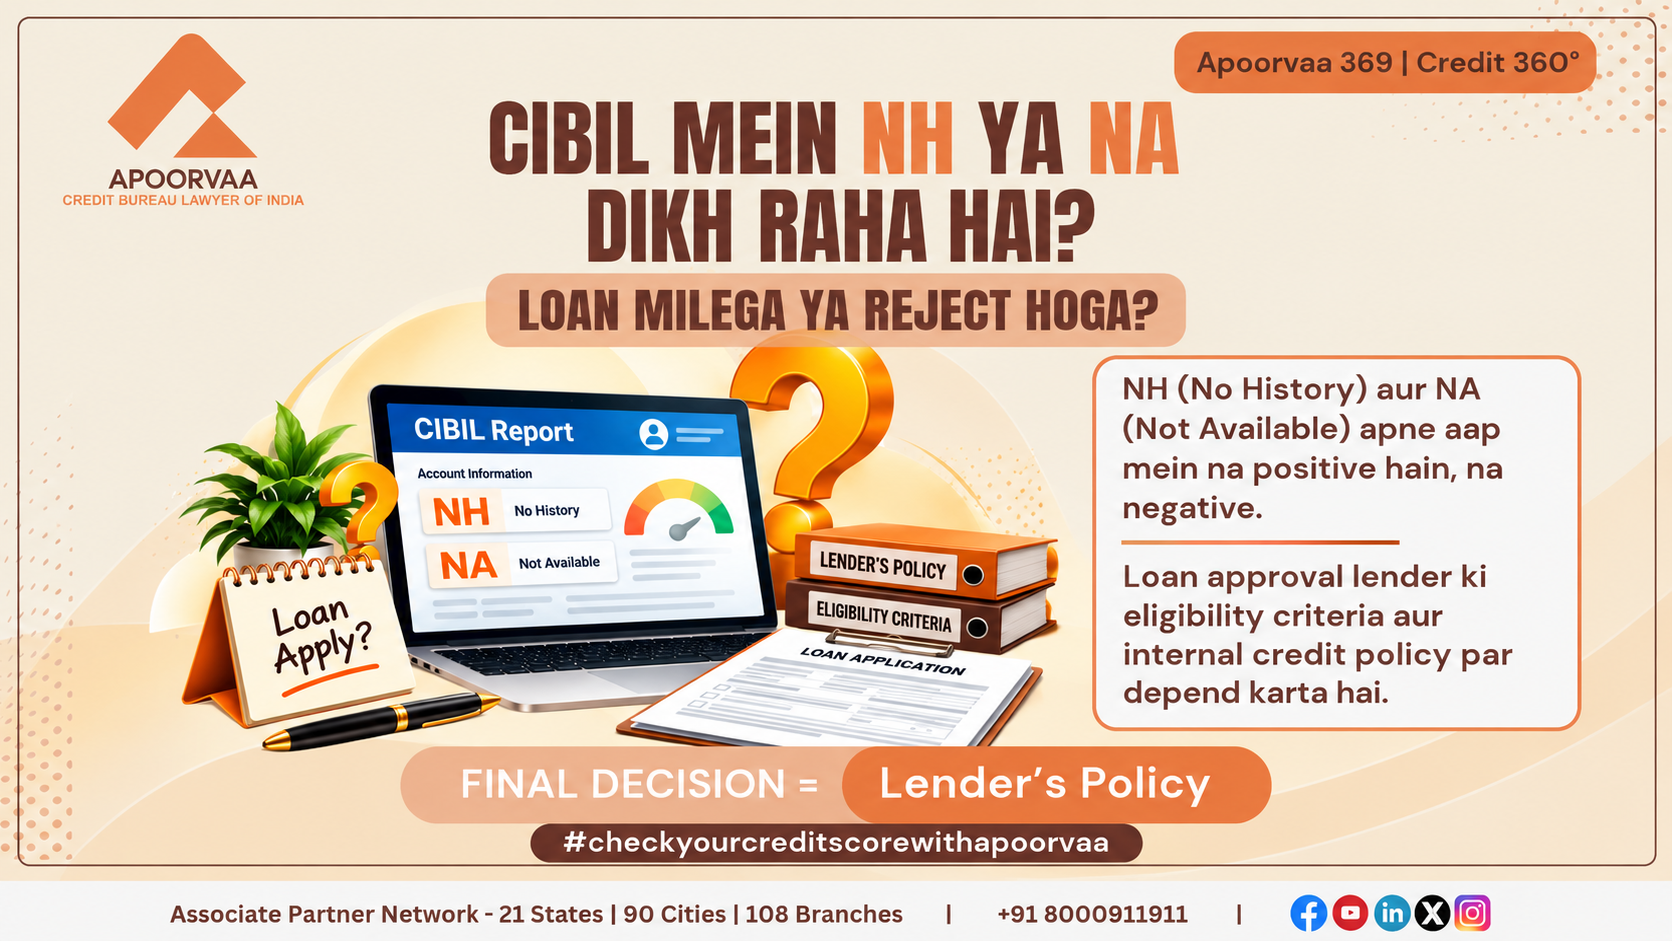
However, NH or NA in CIBIL Score does not automatically indicate bad credit or loan rejection.
These indicators relate to the availability of sufficient credit information for generating a numerical score.
Whether a lender approves a loan application is a separate decision governed by its credit policy, eligibility requirements and assessment of the applicant’s financial circumstances.
Understanding this distinction is important for borrowers, bankers and financial professionals.
1. What Does NH or NA Mean in a CIBIL Report?
According to TransUnion CIBIL’s published consumer guidance:
NH means No History.
NA means Not Available.
These indicators may appear when a numerical CIBIL Score cannot be generated from the available credit information.
A standard numerical CIBIL Score generally ranges from 300 to 900.
However, NH and NA should not be interpreted as numerical scores below 300 or as a separate category of poor creditworthiness.
TransUnion CIBIL identifies three common circumstances associated with NH or NA:
- The consumer has no credit history or insufficient credit history for scoring.
- The consumer has not had credit activity in the last couple of years.
- The consumer holds add-on credit cards but has no independent credit exposure.
Therefore, NH or NA is primarily an indication concerning credit-history availability or score generation.
It does not, by itself, establish that the consumer has defaulted on a loan.
Official reference: TransUnion CIBIL — Know the Difference Between Your CIBIL Score and Report and Contact Us FAQs.
2. Why Is My CIBIL Score Showing NH or NA?
There are several circumstances in which a consumer may receive NH or NA instead of a numerical score.
A. The Consumer Is New to Credit
Consider a 24-year-old salaried employee who has recently started working.
The individual has a regular monthly income but has never obtained a personal loan, vehicle loan or credit card.
When a lender accesses the individual’s credit information, there may be insufficient credit history to calculate a numerical score.
The report may therefore display NH or NA.
This does not mean the individual has a history of missed payments.
It may simply mean that no sufficient repayment track record is available for scoring.
B. The Consumer Has Limited Credit History
A consumer may have recently obtained a credit facility, but the available credit information may not yet be sufficient to generate a numerical score.
TransUnion CIBIL’s consumer guidance explains that numerical score eligibility depends on the availability of an adequate credit history.
However, the precise score-generation outcome depends on the applicable scoring model and available information.
Therefore, consumers should not assume that a numerical score will automatically appear after a fixed number of days.
C. There Has Been No Recent Credit Activity
NH or NA does not necessarily mean that a person has never borrowed.
Consider a borrower who obtained a vehicle loan several years ago, repaid it and subsequently had no further credit activity.
The consumer may have a historical borrowing record but insufficient recent credit information for numerical scoring.
TransUnion CIBIL expressly identifies the absence of credit activity during the preceding couple of years as one possible reason for NH or NA.
This is an important distinction.
No Recent Credit Activity Does Not Mean No Previous Loan Ever Existed.
D. The Consumer Holds Only Add-On Credit Cards
Another situation involves consumers who use add-on credit cards without having independent credit exposure.
For example, an individual may hold an add-on card linked to a family member’s primary credit-card account.
The existence of an add-on card does not necessarily provide the independent credit history needed for numerical scoring.
TransUnion CIBIL includes this situation among the possible reasons for NH or NA.
The precise treatment of an add-on card and its associated information should be understood from the relevant credit records.
3. Is NH or NA a Negative Credit Remark?
No. NH or NA should not automatically be treated as an adverse credit remark.
It is important to distinguish score availability from account-level repayment information.
Consider the following terms:
| Credit-report information | General meaning |
| NH | No History |
| NA | Not Available |
| Settled | May indicate an account resolved through a compromise settlement |
| Written-off | Relates to a lender’s write-off treatment of an account |
| Amount Overdue | An amount reported as overdue on a credit account |
| Repayment Delay | Late-payment information associated with a credit obligation |
These are not interchangeable classifications.
NH or NA does not automatically establish that the borrower has:
- Failed to repay an EMI
- Entered into a loan settlement
- Had a loan written off
- Defaulted on a credit obligation
- Become ineligible for future credit
Equally, NH or NA should not be interpreted as proof that the borrower has an excellent repayment history.
An unavailable numerical score does not provide the same information as a strong, established credit track record.
NH or NA Is Neither Automatically Positive Nor Automatically Negative.
It indicates that a numerical credit score is unavailable in the relevant circumstances.
Any separate adverse account information appearing in the Credit Report must be assessed on its own merits.
4. Can Banks Approve Loans When CIBIL Shows NH or NA?
Yes, loan approval may still be possible.
However, approval is not guaranteed.
This distinction is directly supported by TransUnion CIBIL’s published guidance, which explains that although NH or NA is not inherently negative, some lenders’ credit policies may prevent them from extending loans to applicants without an established credit track record.
This means two financial institutions may assess the same applicant differently.
Illustrative Example
A salaried applicant earns ₹55,000 per month.
The applicant has stable employment, documented income and no substantial existing liabilities.
However, the CIBIL Report displays NH.
Lender A
Its internal lending criteria may permit consideration of applicants without a numerical CIBIL Score.
It may assess employment, income stability, repayment capacity and other eligibility requirements.
The application may proceed for further evaluation.
Lender B
Its internal policy may require an established credit track record or a numerical score for the particular loan product.
The same application may not meet that lender’s eligibility criteria.
Neither outcome automatically proves that NH is a negative credit remark.
The difference may arise from the lenders’ respective underwriting policies.
NH / NA ≠ Automatic Loan Rejection
Final Lending Decision = Lender’s Policy and Applicant’s Overall Eligibility
5. Why Does the Lender’s Credit Policy Matter?
A credit score is one input that lenders may use to evaluate a loan application.
It is not the only factor.
Depending on the loan product and lender, the assessment may include:
Income and Repayment Capacity
The lender may examine whether the applicant’s documented income is sufficient to support the proposed repayment obligation.
Employment or Business Stability
For salaried applicants, employment continuity and income documentation may be relevant.
For self-employed applicants, business income, financial statements and cash-flow information may form part of the assessment.
Existing Financial Liabilities
Existing EMIs and other obligations can influence repayment-capacity calculations.
Loan Type and Security
The lender’s assessment may differ depending on whether the proposed credit facility is secured or unsecured.
Internal Risk and Eligibility Criteria
Each lender may establish requirements concerning income, employment, credit history, exposure limits and other underwriting considerations, subject to applicable law and regulation.
Therefore, the absence of a numerical score does not mean that the lender has no basis for evaluating an applicant.
It means that one commonly used credit-risk indicator may not be available.
The lender must decide whether its policy permits assessment using the other available information.
6. Does NH or NA Mean I Have Never Taken a Loan?
Not necessarily.
This is an important misconception.
NH or NA can arise even when a consumer has borrowed previously.
For example, a person may have obtained and repaid a loan several years ago but has had no recent credit activity.
Another person may have limited credit information that is insufficient for numerical scoring.
A third individual may have only add-on credit-card exposure.
All three situations are different.
Yet each may be associated with NH or NA.
Therefore, a lender or borrower should not conclude from NH or NA alone that the consumer has never had a credit account.
The account information, reporting dates and available credit history must be considered.
A Missing Numerical Score Is Not the Same as a Missing Lifetime Borrowing History.
7. NH or NA vs Low CIBIL Score: What Is the Difference?
A low numerical CIBIL Score and an unavailable numerical score are fundamentally different.
A low score is a calculated result based on the information available to the scoring model.
NH or NA indicates that a numerical score is not available in the relevant circumstances.
| Comparison | NH or NA | Low Numerical CIBIL Score |
| Numerical score available | No | Yes |
| Meaning | Score unavailable or insufficient qualifying credit information | Numerical assessment based on available credit information |
| Automatically indicates default | No | No |
| Automatically means loan rejection | No | No |
| Lender assessment | Depends on policy and overall eligibility | Depends on policy, score and overall eligibility |
A low numerical score may reflect various aspects of the consumer’s credit profile, but it should not automatically be equated with a particular default or adverse account status.
Similarly, NH or NA should not automatically be described as a weak credit score.
An Unavailable Score and a Low Score Are Not the Same Credit-Information Outcome.
8. Does NH or NA Require Credit-Report Correction?
Not automatically.
A consumer may see NH or NA and assume that the Credit Report contains an error requiring rectification.
However, if NH or NA correctly reflects the available credit information, there may be no error to correct.
For example, an individual who has never held an independently reported credit facility may legitimately have insufficient information for numerical scoring.
The absence of a numerical score is not itself proof of incorrect reporting.
A different issue arises where the Credit Report contains inaccurate account information.
For example:
- An account belonging to the consumer is incorrectly omitted.
- An unrelated loan is incorrectly associated with the consumer.
- An account’s ownership information is inaccurate.
- The lender has furnished incorrect account details.
- The report contains an inaccurate outstanding balance or repayment classification.
Such discrepancies may require investigation under the applicable credit-information correction framework.
But they must be established independently of the NH or NA indicator.
Insufficient Information for Scoring ≠ Inaccurate Credit Information
Professional Credit Rectification should focus on genuine reporting inaccuracies rather than promising to convert every NH or NA indicator into a numerical score.
9. Why Should You Check the Complete Credit Report?
When consumers see NH or NA instead of a numerical CIBIL Score, they often focus exclusively on that indicator.
However, the Credit Report contains information beyond the score.
Depending on the consumer’s credit history, it may include:
- Personal identification information
- Credit account details
- Loan and credit-card information
- Current balances
- Amounts overdue
- Repayment history
- Account ownership information
- Credit enquiries
- Relevant reporting dates
A numerical score is an assessment derived from available credit information. The Credit Report provides the underlying account-level information that helps explain the consumer’s credit profile.
This distinction becomes particularly important when NH or NA appears.
For example, a consumer may have an older closed loan account but no recent credit activity sufficient for numerical scoring.
Another consumer may have no independently reported credit accounts.
Both may receive an NH or NA indicator, but their underlying credit histories are different.
Therefore, NH or NA should not be interpreted without reviewing the information available in the report.
A Credit Report Can Contain Useful Credit Information Even When a Numerical Score Is Unavailable.
10. How Should Lenders Interpret NH or NA During Loan Assessment?
The absence of a numerical score creates a different assessment situation from that of a borrower with an established credit score.
It does not automatically establish that the applicant represents a high credit risk.
Nor does it establish that the applicant represents a low credit risk.
The lender must consider the information available under its credit policy.
Applicant A: New-to-Credit Salaried Employee
A salaried employee applies for a vehicle loan.
The applicant has:
- Stable employment
- Documented monthly income
- No substantial existing liabilities
- No established independent credit history
- NH displayed instead of a numerical score
A lender whose policy permits assessment of new-to-credit applicants may consider the application using income, repayment capacity and other eligibility criteria.
Another lender may require an established credit track record for the same loan product.
The outcome can differ without NH being treated as an adverse repayment classification.
Applicant B: Previously Borrowed but No Recent Credit Activity
An individual repaid a loan several years ago and has not used another credit facility recently.
The CIBIL Report displays NH or NA.
This does not automatically mean that the individual has never borrowed.
A lender may consider the available historical account information and other financial details, subject to its underwriting criteria.
Applicant C: Add-On Credit-Card Holder
A consumer uses an add-on credit card linked to a family member’s primary account.
The consumer has no independent credit exposure sufficient for numerical scoring.
NH or NA may appear.
The lender may need to assess the applicant’s eligibility without relying on an established independent repayment track record.
These examples demonstrate why NH or NA should be understood as a score-availability issue, not an automatic loan-eligibility verdict.
11. Can a Loan Be Rejected Even Though NH or NA Is Not Negative?
Yes.
This is an important distinction.
A credit indicator does not have to represent a default or adverse repayment event for a lender to decline an application.
For example, a lender may require a minimum period of established credit history for a particular unsecured loan product.
An applicant whose report displays NH may not meet that requirement.
The lender may decline the application because its underwriting criteria are not satisfied.
That does not mean NH itself is a settlement, write-off or default remark.
Similarly, another lender may permit applications from consumers without a numerical score and evaluate their financial circumstances through other eligible information.
The correct distinction is between:
Credit-Information Classification
and
Lender’s Credit Eligibility Requirements
These are separate matters.
TransUnion CIBIL’s consumer guidance also recognises that some lenders’ credit policies may prevent them from extending credit to applicants without an established credit track record.
Therefore, it would be inaccurate to promise that every consumer with NH or NA can obtain a loan.
It would be equally inaccurate to claim that every such application will be rejected.
12. When Does NH or NA Become a Credit-Report Accuracy Concern?
NH or NA does not automatically require Credit Rectification.
However, a consumer may discover an unrelated reporting discrepancy while reviewing the complete report.
Consider three situations.
Situation 1: NH With No Independent Credit History
A consumer has never held an independently reported credit facility.
The report displays NH.
There is no evidence of incorrect account information.
In this situation, the absence of a numerical score may be entirely consistent with the available credit history.
Situation 2: NH With Older Credit History
A consumer previously held a loan that was repaid several years ago.
There has been no recent credit activity.
The report displays NH or NA.
The indicator alone does not establish that the historical loan information has been incorrectly reported.
The available account details and reporting history must be examined.
Situation 3: NH Alongside a Genuine Account Discrepancy
A consumer identifies an account that does not belong to them or finds that an existing credit account contains inaccurate ownership or repayment information.
This is a different issue.
The potential error concerns the accuracy of the account information, not merely the absence of a numerical score.
Where a reporting discrepancy is supported by the underlying records, investigation and correction may be appropriate under the applicable credit-information framework.
NH / NA Alone ≠ Proof of a Credit-Report Error
Incorrect Account Information = Potential Credit Rectification Issue
The distinction protects consumers from unnecessary concern and helps ensure that genuine inaccuracies receive appropriate attention.
13. What Does India’s Credit-Information Framework Require?
India’s credit-information system operates under the Credit Information Companies (Regulation) Act, 2005, the applicable rules and regulations, and RBI directions.
Credit institutions furnish relevant account information to Credit Information Companies.
The accuracy and updating of this information are important to the credit-information system.
Where a consumer identifies inaccurate credit information, the applicable dispute and correction mechanisms provide a framework for verification and rectification.
However, this framework should not be misunderstood as requiring every NH or NA indicator to be converted into a numerical score.
A score depends on the applicable scoring model and the information available for its calculation.
If the information is insufficient for scoring, the absence of a numerical score is not automatically an error.
What About RBI’s Credit-Information Correction Rules?
RBI’s framework addresses the handling of complaints involving delayed updating or rectification of credit information.
Under the applicable compensation framework, a complainant may be entitled to ₹100 per calendar day when a qualifying credit-information correction complaint remains unresolved beyond 30 calendar days, subject to prescribed conditions.
This does not mean that every consumer displaying NH or NA is entitled to compensation or a numerical score within 30 days.
The issue must involve a qualifying credit-information complaint, and the applicable requirements must be satisfied.
Credit-Information Accuracy and Credit-Score Availability Are Related but Distinct Matters.
14. Can NH or NA Appear Differently Across Credit Bureaus?
India has four Credit Information Companies:
- TransUnion CIBIL
- Experian
- Equifax
- CRIF High Mark
Each bureau operates its own credit-information and scoring systems.
The indicators and score presentation used by one bureau should not automatically be assumed to have identical terminology or calculation rules across all four.
A consumer may therefore encounter different score-availability outcomes when reviewing reports from different CICs.
Such differences do not automatically establish that one report is incorrect.
The relevant questions are whether the underlying account information is accurate, sufficiently current and appropriately associated with the consumer.
For example, if one report contains a loan account and another does not, the difference may justify further examination.
But it should not automatically be described as a reporting error without considering the account details, reporting dates and the applicable bureau’s records.
Professional analysis should distinguish differences in scoring systems from actual account-level inaccuracies.
15. Why Professional Credit-Report Analysis Matters
A consumer may approach a credit professional with a simple request:
“My CIBIL Score shows NH. Please correct it.”
However, the appropriate assessment begins by understanding what the report actually contains.
Does the consumer have an established credit history?
Is there sufficient recent credit information?
Does the report contain an add-on card without independent credit exposure?
Are the existing accounts accurately associated with the consumer?
Are the balances, ownership details and repayment records correct?
These questions help establish whether the concern relates to:
Insufficient Credit Information for Scoring
or
Inaccurate Credit Information Requiring Investigation
The distinction is central to responsible Credit Rectification.
Where the available credit information is accurate but insufficient for a numerical score, there may be no reporting error to correct.
Where the underlying account information is genuinely inaccurate, the discrepancy may require professional review and appropriate rectification.
Apoorvaa’s focus is on credit-information accuracy, account-level verification and evidence-based Credit Rectification.
We do not treat NH or NA as an automatically negative classification or promise that every unavailable score can be converted into a numerical score.
Frequently Asked Questions
1. What is the meaning of NH in CIBIL Score?
NH means No History. It is an indicator associated with the absence of sufficient qualifying credit information for numerical scoring.
2. What does NA mean in CIBIL Score?
NA means Not Available. It indicates that a numerical score is unavailable in the relevant circumstances.
3. Is NH or NA a bad CIBIL Score?
No. NH and NA are not low numerical scores. They should not automatically be interpreted as negative repayment classifications.
4. Can I get a loan if my CIBIL Score shows NH?
Loan approval may still be possible. The outcome depends on the lender’s credit policy, eligibility criteria and assessment of your financial profile.
5. Will every bank reject a loan application showing NA?
No. Different lenders may apply different eligibility and underwriting requirements. NA does not automatically require rejection.
6. Does NH mean I have never taken a loan?
Not necessarily. NH may also be associated with insufficient recent credit activity or other circumstances in which a numerical score cannot be generated.
7. Can NH or NA appear even if I had a loan in the past?
Yes. A consumer with historical borrowing but insufficient recent credit activity may receive NH or NA.
8. Is NH the same as a zero CIBIL Score?
No. NH is not a numerical score of zero and should not be interpreted as one.
9. Does NH or NA mean my loan was written off or settled?
No. NH or NA does not itself represent a settlement or write-off classification. Any such account information must be examined separately.
10. Does NH or NA require Credit Rectification?
Not automatically. Rectification becomes relevant when the underlying credit information is inaccurate, not merely because a numerical score is unavailable.
11. When will my numerical CIBIL Score appear?
There is no universal fixed timeline that can be promised. Score availability depends on the applicable scoring criteria and the credit information available.
12. Can a lender assess my application without a numerical CIBIL Score?
A lender may do so if its policy permits, using relevant financial information and other underwriting criteria. Approval remains subject to its assessment.
My Perspective
In credit-related counselling, I frequently observe that consumers attach too much importance to a single number or indicator without understanding the information behind it.
When a borrower sees NH or NA, the immediate reaction is often:
“Sir, my CIBIL is negative. Will the bank reject my loan?”
My response is that NH or NA should not automatically be interpreted as negative credit behaviour.
It may indicate that sufficient information is unavailable to generate a numerical score.
That is different from a repayment default, loan settlement or write-off.
At the same time, borrowers should understand that the absence of a negative classification does not create an automatic entitlement to credit.
Banks and financial institutions must assess applications according to their lending policies and the applicant’s overall financial circumstances.
I believe three questions are particularly important:
1. Is the numerical score unavailable because of the credit history?
2. Is the underlying Credit Report accurate?
3. Does the lender’s policy permit consideration of an applicant without an established numerical score?
These questions help separate credit-information interpretation from loan eligibility.
They also prevent consumers from seeking unnecessary Credit Rectification when no reporting error exists.
An unavailable score is not automatically a bad score. And a genuine reporting error should never be ignored merely because the score is unavailable.
Final Takeaway
NH or NA in CIBIL Score does not automatically indicate poor creditworthiness or loan rejection.
According to TransUnion CIBIL’s consumer guidance, these indicators may arise when the consumer has insufficient credit history, lacks recent credit activity or holds add-on credit cards without independent credit exposure.
Remember:
NH = No History
NA = Not Available
NH / NA ≠ Low Numerical CIBIL Score
NH / NA ≠ Settlement, Write-Off or Default
NH / NA ≠ Automatic Loan Rejection
NH / NA ≠ Automatic Credit-Report Error
Loan Eligibility = Lender’s Policy + Overall Applicant Assessment
A borrower should understand the complete Credit Report before drawing conclusions from the score field alone.
The correct objective is to establish whether the credit information is accurate and whether the applicant meets the lender’s eligibility requirements.
Does Your CIBIL Report Show NH or NA?
If your CIBIL Report displays NH or NA and you are unsure what the indicator means, Apoorvaa can assist with professional Credit Report analysis.
Where account information appears inaccurate, further verification may establish whether Credit Rectification is justified.
Our approach focuses on:
Credit Report Understanding → Account-Level Verification → Identification of Genuine Discrepancies → Rectification Where Justified
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
NH or NA does not automatically require Credit Rectification. Credit Report analysis does not guarantee generation of a numerical score, a particular credit-score outcome or approval of a loan application.
Related Credit Education
- NOC vs Settlement Letter: Why Does CIBIL Still Show Settled?
- Can You Freeze Your CIBIL Report to Prevent Fake Loans in India?
- EMI Never Paid Late but CIBIL Shows DPD? What Should You Check?
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed