

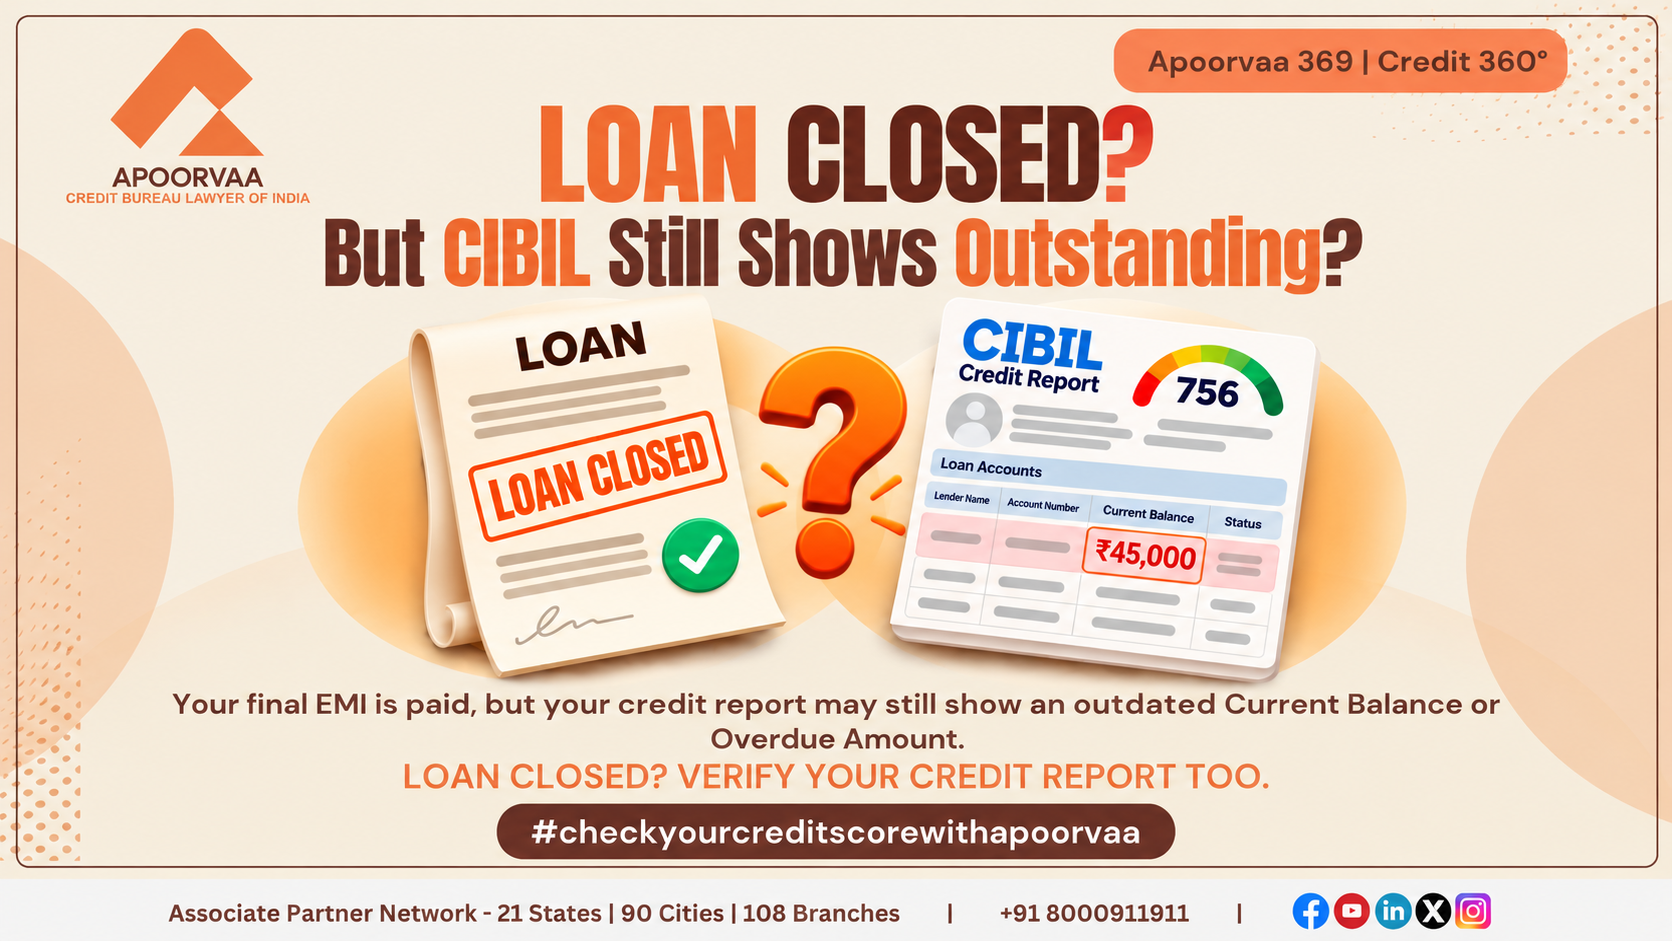
“My loan is fully closed. Why is CIBIL still showing an outstanding balance?”
The customer had completed the loan repayment but discovered that the CIBIL Report continued to show an outstanding amount.
The concern is understandable.
A borrower may have paid every EMI, completed the final repayment and received confirmation from the lending institution that the loan has been closed.
Yet the Credit Report may still contain a Current Balance, Amount Overdue or Account Status that does not appear consistent with the completed repayment.
The borrower naturally asks:
“If the bank has closed my loan, why is the Credit Report still showing that I owe money?”
To understand this situation, we must distinguish three different events:
- Completing repayment of the loan.
- Closing the account in the lending institution’s records.
- Updating the corresponding information in the credit bureau’s records.
These events are connected, but they are not necessarily reflected in every system at the same moment.
Repaying a loan and having its closure accurately reflected in the CIBIL Report are two separate aspects of the same credit relationship.
1. Loan Repayment, Account Closure and Credit Bureau Reporting Are Different
A borrower may consider the loan completed after paying the final EMI.
However, the credit-information system involves more than the payment transaction.
Stage 1: The Borrower Completes Repayment
The borrower pays the outstanding amount required to discharge the loan under its terms.
This may involve the final scheduled EMI or another repayment arrangement permitted by the lending institution.
For example, a borrower may complete the final payment of a vehicle loan on 12 September 2026.
The borrower expects the account to be closed because the required repayment has been completed.
However, the payment transaction alone does not establish what information is currently appearing in the Credit Report.
Stage 2: The Lender Records the Account Closure
The lending institution must recognise the completed repayment and record the appropriate account position in its systems.
Depending on the circumstances, the borrower may receive a loan-closure letter, No Dues Certificate or another document confirming the account’s position.
The lender’s records are important because credit bureaus rely on information furnished by credit institutions.
Stage 3: The Updated Information Reaches the Credit Bureau
The lending institution reports the relevant credit information to credit information companies, including TransUnion CIBIL.
The bureau processes the information received and reflects the reported account position in the consumer’s Credit Report.
Consequently, a borrower may have completed repayment while the latest Credit Report still displays information from an earlier reporting date.
The existence of an outstanding balance immediately after repayment does not, by itself, establish that the lender or credit bureau has committed a reporting error.
The reporting date and the actual account position must be considered together.
2. What Does Current Balance Mean in a CIBIL Report?
Current Balance is one of the most important fields to understand when a borrower discovers an outstanding amount after loan closure.
In the context of a loan account, it represents the outstanding balance reported for that credit facility as of the relevant reporting information.
It should not automatically be interpreted as an overdue amount.
Example: A Loan Repaid After the Last Reporting Date
Consider the following illustrative situation:
| Particulars | Information |
| Loan Type | Personal Loan |
| Balance Before Final Repayment | ₹45,000 |
| Date of Final Repayment | 12 September 2026 |
| Lender’s Confirmed Position | Loan fully repaid |
| Date of Credit Information Displayed | 9 September 2026 |
| Current Balance in Report | ₹45,000 |
Illustrative example only.
The borrower has repaid the loan on 12 September.
However, the Credit Report displays information relating to 9 September, when ₹45,000 was still outstanding.
In this situation, the reported balance may reflect the earlier account position rather than an error in the lender’s current records.
The borrower should therefore consider the reporting date before concluding that the closure has been incorrectly reported.
What Should Happen After Accurate Closure Reporting?
Where a loan has been fully repaid and the lender has correctly recorded its closure, the updated credit information should reflect the appropriate account position.
For an ordinary fully repaid loan, this would generally include:
- A Current Balance of zero.
- No outstanding overdue amount.
- The appropriate closed account status.
- Relevant closure information, where applicable.
The precise presentation may vary by report format and account type.
A historical balance appearing against an earlier reporting date is different from an outstanding amount that continues to be reported after the loan has been fully repaid and the updated information should have been furnished.
3. What Does Amount Overdue Mean?
A borrower may see both Current Balance and Amount Overdue in the same CIBIL Report.
These fields are related to the credit facility, but they do not mean the same thing.
Amount Overdue represents the amount reported as overdue against the account.
An amount can be outstanding without necessarily being overdue.
For example, a borrower may have a home loan with a substantial outstanding principal balance while all scheduled EMIs are being paid on time.
The outstanding balance is not, by itself, evidence of missed repayment.
Current Balance vs Amount Overdue
| Credit Report Field | What It Indicates |
| Current Balance | The reported outstanding balance associated with the credit facility |
| Amount Overdue | The amount reported as overdue |
| Account Status | The reported classification or position of the credit account |
These fields should not be used interchangeably.
Illustrative Example
A customer has an active personal loan with the following reported information:
| Field | Reported Value |
| Current Balance | ₹1,20,000 |
| Amount Overdue | ₹0 |
| Account Status | Active |
The existence of a Current Balance does not mean the borrower has defaulted.
It may simply represent the amount remaining on an active loan.
Now consider a different situation:
| Field | Reported Value |
| Current Balance | ₹45,000 |
| Amount Overdue | ₹12,000 |
| Account Status | Active |
Here, the report indicates both an outstanding balance and an overdue amount.
If the customer has already fully repaid and closed the loan, the accuracy and reporting date of both fields become relevant.
A borrower should not assume that Current Balance and Amount Overdue describe the same financial obligation.
4. What Does Account Status Mean After Loan Closure?
The Account Status field helps describe the reported position or classification of the credit facility.
TransUnion CIBIL’s consumer education material identifies account statuses such as open, closed, settled and written-off. These classifications are not interchangeable.
For a borrower who has completed repayment, the account’s status is important because it helps establish how the lender has reported the conclusion of the credit relationship.
Why a Zero Balance Alone May Not Tell the Complete Story
Consider two accounts:
Account A
- Current Balance: ₹0
- Amount Overdue: ₹0
- Status: Closed
Account B
- Current Balance: ₹0
- Amount Overdue: ₹0
- Status: Settled
Both accounts show zero current outstanding amounts.
However, they do not necessarily represent the same repayment history or the same circumstances of closure.
A fully repaid loan should not automatically be treated as equivalent to an account concluded through a settlement arrangement.
TransUnion CIBIL explains the distinction between a loan repaid in full and a loan reported as settled after payment of an agreed amount lower than the complete dues. CIBIL
Similarly, a write-off classification has a different meaning from ordinary full repayment.
Current Balance, Amount Overdue and Account Status must be read together to understand the reported account position.
5. Why Does CIBIL Still Show Outstanding After the Final EMI?
There may be several explanations.
The most important distinction is between a normal reporting interval and information that remains inaccurate or outdated after the relevant reporting cycle.
Reason 1: The Credit Report Contains an Earlier Reporting Date
Suppose the customer repays a loan on 12 September.
The latest account information available in the Credit Report may relate to 9 September.
The balance appearing in that report may therefore represent the position before the final repayment.
This does not automatically establish incorrect reporting.
The relevant question is whether the updated account position has subsequently been furnished and reflected.
Reason 2: The Lender Has Not Yet Reported the Updated Closure Information
The lending institution may have recorded the repayment but the updated closure information may not yet have reached the credit bureau.
This is why the lender’s account position and the bureau’s displayed account information may temporarily differ.
The borrower should not assume that a loan-closure letter causes the credit bureau’s records to change immediately.
Reason 3: The Updated Information Does Not Accurately Reflect the Closure
In some cases, the account may continue to show an outstanding balance, overdue amount or incorrect status even after the relevant updated reporting should have taken place.
The discrepancy may relate to the information furnished by the lending institution or its processing in the credit-information system.
This situation differs from a report that merely contains an earlier reporting date.
Reason 4: The Borrower Has Misunderstood the Nature of the Closure
A customer may describe a loan as closed because an agreed settlement amount was paid.
However, a settlement is not necessarily equivalent to repayment of the entire contractual obligation.
Likewise, a write-off should not be interpreted as automatic waiver of the borrower’s liability.
The actual account history and lender-confirmed position matter.
Before identifying a Credit Rectification concern, it is necessary to understand whether the account was fully repaid, settled or otherwise classified.
6. What Are the RBI Credit Reporting Requirements in 2026?
This is particularly important for borrowers who are still relying on older information suggesting that credit bureaus are updated only once every 30–45 days.
The reporting framework has changed.
The RBI’s amendments issued in December 2025 took effect on 1 July 2026, establishing more frequent reporting requirements for credit institutions.
Reporting Reference Dates
Under the updated framework, credit institutions are required to report credit information with reference to:
| Reporting Reference Date |
| 9th day of the month |
| 16th day of the month |
| 23rd day of the month |
| Last day of the month |
The framework also provides for monthly full-file submissions and interim submissions covering relevant changes, including account closures.
Does This Mean CIBIL Must Show a Closed Loan Immediately After Payment?
No.
The reporting reference dates are not a promise that every payment or account closure will become visible to the consumer immediately.
The process involves the lender’s account records, the relevant reporting reference date, submission of information and processing by the credit information company.
For example, a loan repaid after one reporting reference date may be reflected through a subsequent reporting cycle.
The exact position should be assessed against the applicable requirements and the dates relevant to the particular account.
Why Older 30–45 Day Explanations Require Care
Some older TransUnion CIBIL consumer guidance refers to a general 30–45 day reporting interval.
However, when preparing a September 2026 authority article, that older explanation should not be presented as the current RBI-mandated reporting frequency.
The current regulatory framework must take precedence when describing applicable reporting obligations.
The correct approach is to examine the actual repayment date, lender-confirmed closure date, Credit Report reporting date and applicable reporting requirements together.
7. Why the Date Reported Field Is Important
A borrower may see an outstanding balance and immediately conclude:
“The bank has not updated my loan closure.”
However, the date associated with the reported account information may provide important context.
Consider the following illustrative examples.
Example A: The Report Reflects an Earlier Account Position
| Particulars | Date |
| Information Reported As Of | 9 September 2026 |
| Final Loan Repayment | 12 September 2026 |
| Customer Checks Report | 13 September 2026 |
The report may still contain the balance that existed before repayment.
The information should not automatically be classified as inaccurate merely because the customer checked it one day after closing the loan.
Example B: The Account Continues to Show an Incorrect Balance After Updated Reporting
| Particulars | Information |
| Final Loan Repayment | 12 September 2026 |
| Lender Confirms Full Closure | 12 September 2026 |
| Later Account Information | Still shows outstanding balance |
| Customer’s Concern | Report does not reflect confirmed closure |
In this situation, the account information may require closer examination.
The key distinction is whether the balance represents a legitimate earlier reporting position or an account discrepancy that remains after updated reporting should have occurred.
The date associated with the account information helps distinguish a reporting interval from a potentially inaccurate post-closure record.
8. What Is the Importance of a No Dues Certificate or Loan-Closure Letter?
When a borrower completes repayment, documentary confirmation from the lending institution can be important.
Depending on the loan and lender, relevant documents may include:
- No Dues Certificate.
- Loan-closure letter.
- No Objection Certificate.
- Final repayment confirmation.
- Relevant loan account statement.
These documents may help establish the lender-confirmed account position.
For example, a loan-closure letter may confirm that the relevant facility was closed on a particular date.
A loan account statement may help establish the repayment history and final account position.
Does a No Dues Certificate Automatically Update CIBIL?
No.
A No Dues Certificate is evidence of the lender-confirmed position; it is not itself a mechanism that automatically changes the bureau’s database.
The relevant credit information must be accurately furnished and processed through the credit-reporting system.
TransUnion CIBIL states that it cannot independently modify credit information without confirmation from the relevant credit institution.
A borrower should preserve appropriate closure evidence and separately verify whether the Credit Report accurately reflects the completed repayment.
9. When Does a Reporting Delay Become a Credit Report Accuracy Concern?
One of the most important distinctions in post-closure credit reporting is the difference between information that has not yet been updated and information that remains inaccurate after the relevant reporting process.
Consider a borrower who completes the final repayment on 12 September 2026.
If the Credit Report still displays information reported as of 9 September, the outstanding balance may represent the account’s position before repayment.
That is different from a situation where the lender has confirmed full closure but subsequently reported the account as active with an outstanding balance that no longer exists.
Understanding the Difference
| Situation | What It May Indicate |
| Final EMI paid after the report’s reference date | The report may reflect the earlier account position |
| Lender has confirmed closure, but the next reporting cycle has not been completed | The updated closure may not yet be visible |
| Account continues to show an incorrect balance after updated reporting | The information may require rectification |
| Current Balance is zero, but Account Status remains inaccurate | The account classification may require examination |
| Current Balance is zero and Account Status is Closed, but earlier repayment delays remain visible | Historical credit information may still be accurately reported |
The distinction is important because the objective is not simply to obtain a zero balance.
The objective is to ensure that the reported information accurately reflects the loan’s actual position and repayment history.
TransUnion CIBIL acknowledges that recently paid or closed accounts may not immediately reflect updated information and that the lender’s confirmation is required for corrections to reported account details.
10. Why an Outdated Outstanding Balance May Matter During a New Loan Application
A borrower may have completed an earlier personal loan and subsequently apply for a home loan.
However, the Credit Report may still show the earlier loan as active with an outstanding balance.
The borrower may believe that the old loan should no longer be relevant because repayment has been completed.
The lending institution assessing the new application may nevertheless encounter the information appearing in the Credit Report.
Illustrative Example
| Particulars | Actual Position | Credit Report Position |
| Previous Personal Loan | Fully repaid | Active |
| Current Balance | ₹0 | ₹45,000 |
| Amount Overdue | ₹0 | ₹8,000 |
| Account Status | Closed | Not updated |
Illustrative example only.
The customer’s actual financial position and reported credit information are inconsistent.
If the new lender considers the outdated information, it may seek clarification or include the reported obligation in its assessment.
However, an outdated outstanding balance does not automatically establish that a new loan application will be rejected.
Loan decisions may also depend on income, repayment capacity, existing liabilities, lending policies and other eligibility criteria.
Accurate post-closure reporting helps ensure that a lender evaluates the borrower using information that correctly represents the previous credit relationship.
11. Does Closing a Loan Remove Its Entire History From CIBIL?
No.
This is another common misunderstanding.
A borrower may assume that once a loan is fully repaid, the entire account should disappear from the CIBIL Report.
However, loan closure and deletion of historical credit information are different matters.
A closed account may continue to appear as part of the consumer’s credit history.
The account may contain information about its opening date, closure date, earlier repayment behaviour and relevant account classifications.
TransUnion CIBIL’s consumer-awareness guidance specifically explains that closed accounts remain in the report as credit history.
What Should Change After Full Repayment?
For an ordinary fully repaid loan, the current account information should accurately reflect the completed repayment.
This generally means:
- Current Balance should reflect zero outstanding dues.
- Amount Overdue should reflect zero.
- Account Status should reflect the appropriate closure classification.
- Relevant closure information should be accurately reported.
However, accurate historical repayment information may remain visible.
What If There Were Earlier EMI Delays?
Suppose a borrower missed an EMI during the loan tenure but subsequently repaid all dues and closed the account.
The completed repayment does not automatically establish that the earlier delay was incorrectly reported.
A loan can be fully closed while its historical repayment information continues to reflect earlier events.
Current account closure and historical repayment accuracy must be understood separately.
12. Fully Repaid, Settled and Written-Off Accounts Are Not the Same
A customer may say:
“My loan is closed, so why is CIBIL still showing negative information?”
However, the meaning of closure depends on how the underlying credit facility was resolved.
Fully Repaid Loan
The borrower has completed the repayment required to discharge the loan in full.
The lender’s records should reflect the completed repayment, and the corresponding credit information should accurately represent the account’s position.
Settled Loan
A settlement may involve the lender agreeing to accept an amount lower than the total contractual dues as part of a negotiated resolution.
The resulting credit reporting may differ from an ordinary fully repaid account.
A zero Current Balance does not automatically establish that the loan was repaid in full.
Written-Off Loan
A write-off is an accounting treatment applied by a lending institution.
It should not automatically be interpreted as cancellation of the borrower’s repayment obligation.
The actual legal and financial position depends on the underlying circumstances and applicable arrangements.
TransUnion CIBIL’s guidance distinguishes settled and written-off classifications from ordinary account closure.
Why This Distinction Matters
Consider three accounts:
| Account | Current Balance | Reported Status |
| Loan A | ₹0 | Closed |
| Loan B | ₹0 | Settled |
| Loan C | ₹0 | Written-Off |
Illustrative example only.
All three may display a zero Current Balance.
However, the reported classifications do not necessarily represent the same repayment circumstances.
A zero balance is important, but it should not be interpreted independently of the account’s reported status and actual history.
13. Who Is Responsible for Correcting an Incorrect Outstanding Balance?
A common customer question is:
“Should I approach the bank or CIBIL?”
The credit-information system involves both the lending institution and the credit information company.
Their roles are connected but distinct.
The Lending Institution
The lender maintains the underlying loan account records.
It is responsible for accurately furnishing relevant credit information, including applicable repayment and closure information, to credit information companies.
Where the borrower disputes the reported account position, the lender’s records may be essential in establishing whether the information is accurate.
The Credit Information Company
The credit information company maintains and processes credit information furnished by credit institutions.
It also provides mechanisms for consumers to raise concerns about information appearing in their Credit Reports.
However, TransUnion CIBIL explains that it cannot independently change credit information without confirmation from the relevant credit institution.
Why Both Roles Matter
Suppose the lender’s records correctly show that the loan was fully repaid, but the Credit Report continues to display an outstanding balance.
The concern may involve whether the correct information was furnished and subsequently reflected in the bureau’s records.
Alternatively, the lender’s own account records may not yet reflect the correct closure position.
These circumstances require different examination.
The appropriate rectification concern depends on where the actual account information and reported credit information differ.
14. What Does the RBI Say About Delayed Credit Information Rectification?
The Reserve Bank of India introduced a compensation framework for delayed updation or rectification of credit information through its circular dated 26 October 2023.
Under the framework, an eligible complainant may be entitled to compensation of ₹100 per calendar day where a qualifying complaint remains unresolved beyond 30 calendar days from the date of initial filing.
The applicability of compensation and the responsibility for payment depend on the framework’s conditions and the circumstances of the complaint.
Does Every Outstanding Balance Qualify for Compensation?
No.
The compensation framework should not be interpreted as an automatic payment for every instance where a recently closed loan remains visible in a Credit Report.
There is a distinction between:
- A loan that has recently been repaid and is awaiting the applicable reporting process.
- A qualifying complaint concerning inaccurate credit information that remains unresolved beyond the prescribed complaint-resolution period.
The 30-calendar-day complaint-resolution framework is also different from the regular credit-information reporting schedule.
A reporting reference date and a complaint-resolution deadline serve different purposes.
15. Why a No Dues Certificate Matters but Does Not Complete the Reporting Process
A No Dues Certificate or loan-closure letter may be important evidence that the lending institution has confirmed the repayment position.
However, possessing the document does not automatically mean that the Credit Report has been updated.
Consider a customer who has:
- Paid the final EMI.
- Received the loan-closure letter.
- Obtained a No Dues Certificate.
- Confirmed that the lender considers the loan closed.
The customer may still need to verify whether the Credit Report reflects the corresponding account position.
What Can Closure Documents Help Establish?
Appropriate repayment and closure evidence may help establish:
| Document | Potential Relevance |
| Loan-Closure Letter | Lender-confirmed closure of the relevant credit facility |
| No Dues Certificate | Confirmation of the lender’s stated dues position |
| Loan Account Statement | Repayment transactions and account history |
| Final Payment Confirmation | Evidence of the final repayment transaction |
The relevance of each document depends on its wording and the underlying loan arrangement.
A closure document supports verification of the actual account position; it does not automatically alter the bureau’s records.
16. Why Professional Credit Report Review May Be Necessary After Loan Closure
A customer may approach Apoorvaa and explain:
“Sir, my loan is completely closed. I have the No Dues Certificate, but CIBIL still shows ₹45,000 outstanding.”
The customer’s concern appears straightforward.
However, professional examination should distinguish between several possibilities.
Situation 1: The Report Reflects an Earlier Date
The loan may have been repaid after the date of the account information displayed in the report.
The apparent inconsistency may therefore relate to the reporting interval.
Situation 2: The Current Balance Is Incorrect
The lender may have confirmed full repayment, but the updated report continues to show an outstanding amount inconsistent with the actual account position.
Situation 3: The Amount Overdue Is Incorrect
The report may continue to display overdue information that does not accurately represent the account’s current position.
Situation 4: The Account Status Is Incorrect
The balance may have become zero, but the account’s reported status may not accurately reflect the completed repayment.
Situation 5: The Account Was Settled Rather Than Fully Repaid
The customer may describe the account as closed, while the lender’s records reflect a settlement arrangement.
The reporting concern cannot be assessed accurately without understanding that distinction.
At Apoorvaa – Credit Bureau Lawyer of India, professional Credit Report assessment focuses on identifying the actual account-level discrepancy and understanding whether the reported information accurately reflects the customer’s credit history.
The objective is not to promise deletion of every adverse entry.
It is to distinguish genuine inaccuracies from accurately reported account information.
Frequently Asked Questions
1. My loan is fully closed. Why does CIBIL still show an outstanding balance?
The report may reflect an earlier reporting date, or the updated closure information may not yet have been furnished and processed. If the balance remains inaccurate after updated reporting, the account information may require examination.
2. Should Current Balance become zero after full repayment?
For an ordinary fully repaid loan, the updated Current Balance should generally reflect zero outstanding dues.
3. Is Current Balance the same as Amount Overdue?
No. Current Balance represents the reported outstanding balance, while Amount Overdue represents the amount reported as overdue.
4. Can my CIBIL Report show a closed loan?
Yes. Closed accounts may remain visible as part of the consumer’s credit history.
5. Does a No Dues Certificate automatically update CIBIL?
No. It may support verification of the lender-confirmed account position, but the updated credit information must be furnished and processed.
6. Can an old outstanding balance affect a new loan application?
It may be relevant to a lender’s assessment if the information is considered during the application. However, it does not automatically establish that a loan will be rejected.
7. Will my CIBIL Score increase immediately after correcting the balance?
Not necessarily. The effect on the score depends on the credit information and applicable scoring methodology. An immediate increase should not be promised.
8. Does full repayment remove earlier EMI delays?
No. Accurate historical repayment information may remain even after the account is closed.
9. Is a settled loan the same as a fully repaid loan?
No. A settlement arrangement may involve payment of an agreed amount lower than the complete contractual dues.
10. Can an inaccurate outstanding balance be corrected?
Where the reported information does not accurately reflect the actual account position, it may be appropriate to pursue rectification through the relevant credit-information process.
My Perspective: Loan Repayment Is Complete Only When You Also Verify the Credit Report
A customer recently raised an important concern:
“My loan is fully closed. Why is CIBIL still showing an outstanding balance?”
This question highlights a gap in how many borrowers understand loan closure.
A borrower may complete every EMI and receive confirmation from the bank.
However, the borrower should also understand whether the corresponding Credit Report accurately reflects that closure.
Paying the loan is one event.
Recording the closure in the lender’s systems is another.
Having accurate information reflected in the credit bureau’s records is a further step.
These events are connected, but they are not necessarily simultaneous.
My advice is to review the complete Credit Report after loan closure—not merely the numerical score.
Understand the Current Balance, Amount Overdue, Account Status and reporting date.
If the information represents an earlier reporting position, that context matters.
If it remains inconsistent with the actual account position after updated reporting, the discrepancy deserves attention.
Completing repayment is important. Ensuring that your Credit Report accurately reflects that repayment is equally important for your future credit profile.
Final Takeaway
Loan Closed but CIBIL Shows Outstanding Balance? Here’s Why
An outstanding amount appearing after loan closure does not automatically establish incorrect reporting.
The Credit Report may temporarily reflect an earlier account position.
However, once the lender has confirmed full repayment and the relevant updated information should have been reported, the account should accurately reflect its current position.
For an ordinary fully repaid loan, this generally means a zero Current Balance, no outstanding overdue amount and the appropriate closed status.
Historical repayment information may still remain.
Do not confuse full repayment with settlement or write-off.
Do not assume that a No Dues Certificate automatically updates CIBIL.
And do not wait until your next home loan, car loan or business loan application to discover that an old account has not been accurately updated.
Your final EMI completes the repayment. Your Credit Report should accurately reflect the closure.
Professional Credit Report Assessment & Rectification
Loan closed, but your CIBIL Report still shows an outstanding balance or overdue amount?
If your lender has confirmed full repayment but the updated Credit Report does not accurately reflect the account’s actual position, professional assessment may help identify the reporting concern.
Apoorvaa – Credit Bureau Lawyer of India provides professional Credit Report assessment and Credit Rectification services for individuals and businesses.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee immediate score improvement, deletion of accurately reported information or future loan approval.
Related Credit Education
- Unknown Loan in CIBIL Report: What If You Never Took That Loan?
- Loan Closed but CIBIL Shows Settled? Understand the Difference
- Write-Off in CIBIL Report: Does It Mean Your Loan Is Waived?
About the Author
Advocate Apurva Bhagat is the Founder & Chairman of Apoorvaa – Credit Bureau Lawyer of India.
His work focuses on credit-bureau law, Credit Rectification and helping individuals and businesses understand credit-information accuracy, account-level reporting discrepancies and the role of credit information in lending decisions.

Alive But CIBIL Report Shows ‘Deceased’? What Should You Do?
[…] Loan Closed but CIBIL Shows Outstanding […]