

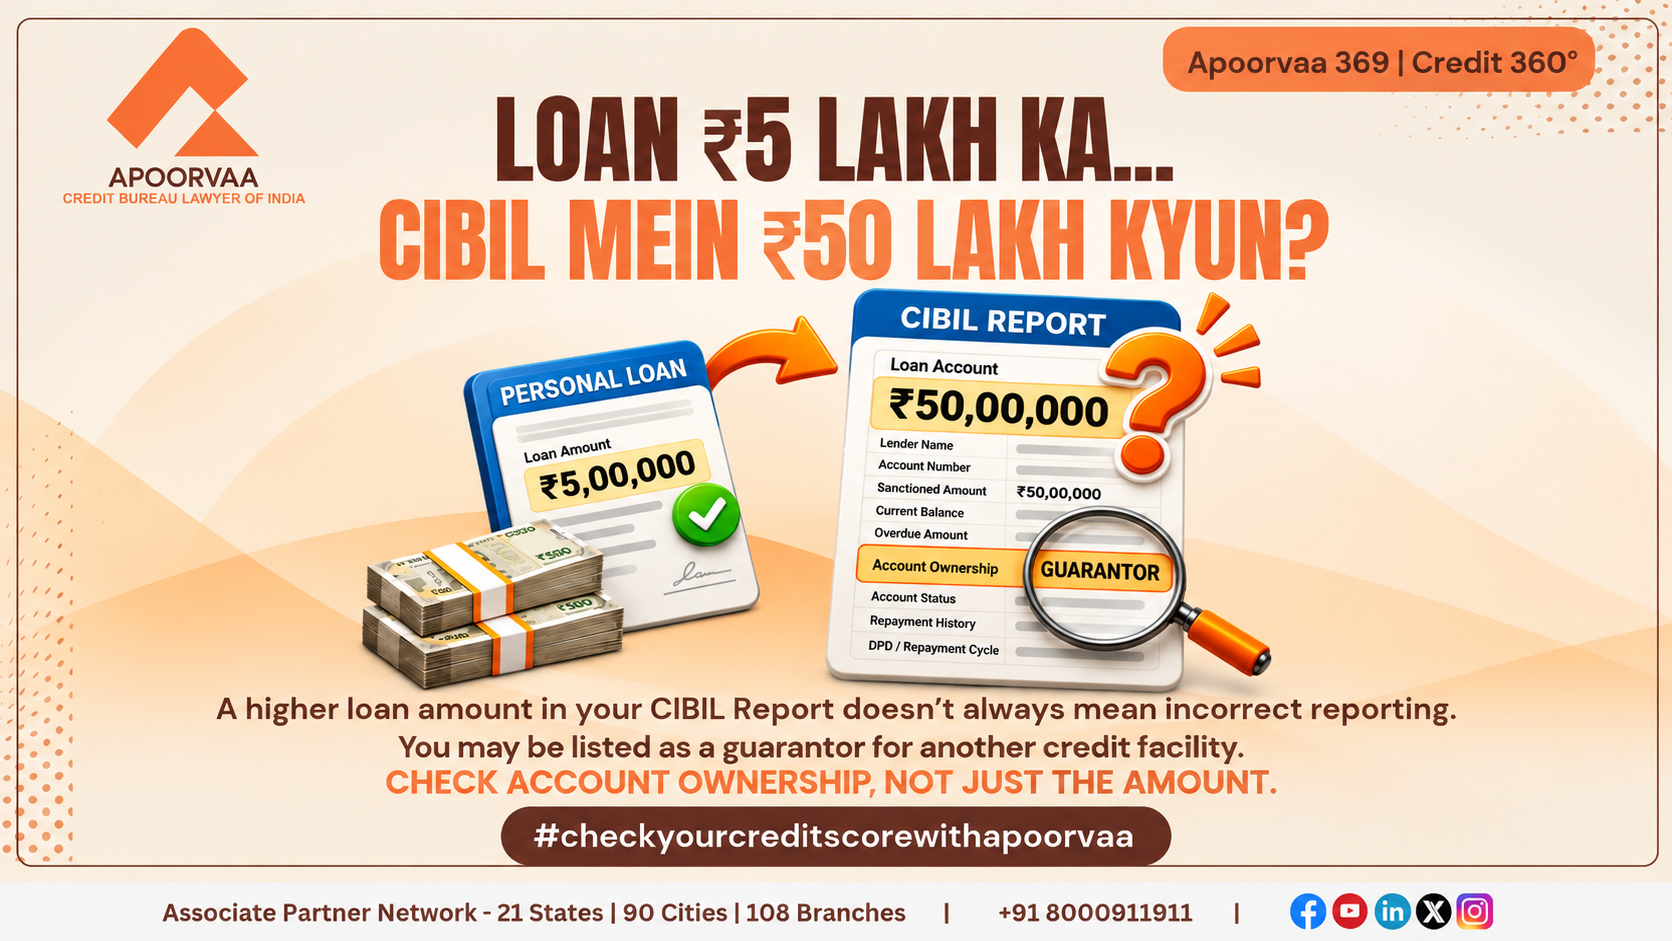
“I took a loan of ₹5 lakh, but my CIBIL Report shows a ₹50 lakh loan. Has the bank reported the wrong amount?”
Imagine discovering an account of ₹50 lakh in your Credit Report when the loan you personally borrowed was only ₹5 lakh.
Your immediate reaction might be that the lender has made a serious reporting error.
But before reaching that conclusion, one important detail must be examined:
What is your relationship with the ₹50 lakh loan?
A Credit Report can contain information about loans you borrowed directly as well as credit facilities for which you provided a guarantee.
This distinction was central to a case we encountered at Apoorvaa.
The customer recognised their own ₹5 lakh borrowing but was concerned about a separate ₹50 lakh account. On detailed examination, the larger facility was associated with a guarantee the customer had provided.
The customer had not personally borrowed ₹50 lakh as the primary borrower.
However, the guarantee created a separate credit relationship that required consideration.
The case illustrates why Guarantor Status in CIBIL Report should be examined before concluding that a loan amount has been incorrectly reported.
1. Why Is a ₹50 Lakh Loan Showing When I Borrowed Only ₹5 Lakh?
A Credit Report is not simply a statement of how much money a person personally received from banks.
It can also contain information about other credit obligations associated with that person.
Consider this illustrative situation:
Personal loan: ₹5 lakh
Separate loan guaranteed: ₹50 lakh
If the individual genuinely provided a guarantee for the ₹50 lakh facility, that association may be reflected in their credit information.
This does not mean the lender has necessarily changed the ₹5 lakh personal loan into a ₹50 lakh loan.
It may mean that two different credit relationships are appearing in the report.
This is why the sanctioned amount alone cannot establish a reporting error.
The account ownership, lender details, account identifiers and nature of the credit relationship must be understood together.
2. Can a Guarantor’s Loan Appear in a CIBIL Report?
Yes.
TransUnion CIBIL’s official consumer FAQ specifically addresses why loans for which a person acts as guarantor can appear in their Credit Report.
A guarantee is not necessarily invisible to the credit-information system merely because the guarantor did not personally receive the loan proceeds.
The guarantee may create a legally relevant financial obligation, depending on the terms of the guarantee and applicable law.
Therefore, where a person has genuinely guaranteed a credit facility, its appearance in their Credit Report is not automatically incorrect.
However, the information must still accurately identify the person’s relationship with that account.
Being a guarantor is different from being the primary borrower.
That distinction should be properly understood before a Credit Report discrepancy is alleged.
3. Borrower vs Joint Borrower vs Guarantor: What Is the Difference?
These three relationships should not be treated as interchangeable.
Primary Borrower
The primary borrower is the person or entity that obtains the credit facility and undertakes the principal repayment obligations under the loan arrangement.
For example, if you personally take a ₹5 lakh loan, you are the borrower for that facility.
Joint Borrower
A joint borrower participates in the borrowing arrangement with another borrower.
The extent and nature of each joint borrower’s obligations depend on the applicable loan documentation and legal framework.
A joint borrower should not automatically be treated as merely a guarantor.
Guarantor
A guarantor provides a guarantee in connection with another person’s or entity’s obligation.
Under Section 126 of the Indian Contract Act, 1872, a contract of guarantee involves a person undertaking to perform a promise or discharge the liability of another person in the event of that person’s default.
The person providing the guarantee is referred to as the surety.
Section 128 further provides that the surety’s liability is co-extensive with that of the principal debtor unless the contract provides otherwise.
In practical terms, a guarantee is not merely a formality.
Its scope and consequences must be understood from the applicable law and the actual guarantee documentation.
Important: A guarantor’s name appearing in a Credit Report does not, by itself, establish that the guarantor personally received the entire sanctioned loan amount.
4. Does a ₹50 Lakh Sanctioned Amount Mean ₹50 Lakh Is Overdue?
No.
This is another important distinction.
A Credit Report may contain several different monetary fields. They do not all represent the same thing.
Sanctioned Amount
The amount sanctioned under the relevant credit facility.
In our illustrative example, this may be ₹50 lakh.
Current Balance
The balance being reported against the account at the relevant reporting date.
This is not necessarily equal to the original sanctioned amount.
Amount Overdue
The amount reported as overdue under the applicable account and reporting position.
An overdue amount should not be confused with the entire sanctioned amount.
Account Status
The reported position of the credit facility, which may include an active, closed, settled, written-off or another applicable status.
Repayment History
Information concerning the account’s payment performance over the periods reflected in the report.
Therefore:
₹50 lakh sanctioned ≠ ₹50 lakh currently outstanding.
And:
₹50 lakh sanctioned ≠ ₹50 lakh overdue.
These distinctions become particularly important when the individual is associated with the account as a guarantor rather than the primary borrower.
5. What Legal Responsibility Can a Loan Guarantor Have?
A person should never assume that providing a guarantee is merely helping someone complete a loan application.
A valid guarantee can create enforceable obligations.
As explained earlier, Section 128 of the Indian Contract Act establishes the general principle of co-extensive surety liability, unless the contract provides otherwise.
However, the exact scope of a guarantor’s obligation requires examination of the guarantee terms and relevant legal circumstances.
For example, the guarantee may contain provisions concerning:
- The obligations covered by the guarantee
- Any contractual limit on liability
- The circumstances in which the guarantee may be invoked
- The duration or continuing nature of the guarantee
- Other applicable contractual conditions
The mere appearance of a sanctioned amount in a Credit Report does not establish the amount presently recoverable from the guarantor.
Equally, the fact that the guarantor did not personally use the loan proceeds does not automatically eliminate the guarantee obligation.
A credit-reporting question and a guarantor-liability question are related, but they are not identical.
6. Why the Complete Credit Report Matters More Than a Single Amount
Returning to our customer example:
The initial concern was straightforward:
“My loan was ₹5 lakh. Why am I seeing ₹50 lakh?”
But the detailed account information revealed something the amount alone could not explain.
The larger facility was connected with the customer’s guarantor relationship.
That changed the nature of the enquiry.
Instead of immediately treating the ₹50 lakh entry as an inflated personal loan, the relevant question became:
“Is this guarantee correctly associated with the customer, and is the account information accurate?”
A meaningful assessment may involve examining the lender name, account identifiers, date opened, sanctioned amount, ownership classification, Current Balance, overdue, account status and repayment history.
These details help distinguish three possibilities:
- A genuine personal borrowing.
- A genuine credit facility associated with the person as guarantor.
- An account or guarantee that has been incorrectly attributed or reported.
The third possibility can raise a genuine Credit Report accuracy concern.
But the first two should not automatically be classified as reporting errors merely because the sanctioned amounts are different.
The account relationship must be established before deciding whether Credit Rectification is required.
7. When Is Guarantor Reporting Correct, and When Could It Be an Error?
The appearance of a guaranteed loan in a Credit Report is not automatically an error.
If an individual genuinely provided a guarantee for a ₹50 lakh credit facility, that relationship may legitimately form part of their credit information.
However, a genuine guarantee does not automatically mean every reported account detail is accurate.
Consider two situations.
Situation 1: The Guarantee Was Actually Provided
The individual signed the relevant guarantee documentation, and the account is correctly associated with them as a guarantor.
In this situation, the sanctioned amount being higher than their personal borrowing does not, by itself, establish incorrect reporting.
Situation 2: The Guarantee Was Never Provided
The individual has no identifiable borrowing or guarantee relationship with the reported account.
This raises a different question concerning account ownership, attribution or inaccurate credit information.
A discrepancy may also arise where the guarantee is genuine but the ownership classification, balance, overdue, account status or repayment history is materially inaccurate.
The objective should be to establish what is correct and what requires rectification, rather than assuming the entire account must be deleted.
8. What If the Report Shows You as the Borrower Instead of the Guarantor?
Account ownership classification is particularly important.
Suppose an individual genuinely guaranteed a ₹50 lakh facility but the Credit Report appears to classify them as the primary borrower.
That difference deserves examination.
A borrower and a guarantor may have different contractual relationships with the underlying credit facility.
The fact that a guarantor can have substantial legal liability does not mean their role should automatically be described as direct borrowing.
Where the ownership classification materially conflicts with the actual loan and guarantee documentation, professional Credit Report assessment may be appropriate.
The objective is accurate classification—not automatic removal of a genuine credit obligation.
9. What Is the Role of the Lender and Credit Bureau?
Banks and other eligible Credit Institutions furnish credit information to Credit Information Companies under the applicable regulatory framework.
The relevant Credit Institution is therefore important when the accuracy of lender-furnished account information is questioned.
TransUnion CIBIL provides a dispute-resolution mechanism for consumers who identify potentially inaccurate information in their reports.
However, lender-furnished information generally requires verification through the concerned Credit Institution before the bureau can modify it.
For a disputed guarantor account, the relevant questions may concern:
- Whether the guarantee relationship actually exists
- Whether the account is attributed to the correct individual
- Whether the ownership classification is accurate
- Whether the reported financial information corresponds with the verified account position
A dispute is not an automatic deletion mechanism.
It is a means of examining information that may be inaccurate.
10. When Does Professional Credit Rectification Become Relevant?
Professional examination becomes particularly relevant when:
- A loan appears against an individual who never borrowed or guaranteed it.
- A genuine guarantor appears to be incorrectly classified as the primary borrower.
- The sanctioned amount, Current Balance or Amount Overdue is materially inconsistent with verified information.
- The account status or repayment history requires examination.
- The reported account cannot be properly connected with the individual’s credit relationship.
At Apoorvaa – Credit Bureau Lawyer of India, our focus is on understanding the complete account information before determining whether Credit Rectification is appropriate.
A ₹50 lakh account appearing alongside a ₹5 lakh personal loan may initially look alarming.
But the amount alone cannot establish whether the entry is correct.
The relationship between the individual and the credit facility is the starting point.
Frequently Asked Questions
1. Can a ₹50 lakh loan appear in my CIBIL Report if I personally borrowed only ₹5 lakh?
Yes. If you genuinely provided a guarantee for a separate ₹50 lakh facility, that credit relationship may appear in your report. Its appearance does not automatically mean your ₹5 lakh loan was incorrectly increased.
2. Does a ₹50 lakh guarantor account mean I owe ₹50 lakh immediately?
No such conclusion should be drawn from the sanctioned amount alone. The extent of any enforceable obligation depends on the guarantee terms, applicable law and relevant circumstances. The sanctioned amount, Current Balance and Amount Overdue are different concepts.
3. Can a guarantor’s credit profile be affected by the guaranteed loan?
Yes. A guarantee can have credit implications, particularly where the underlying facility experiences repayment problems. A guarantee should not be treated as merely a formality.
4. Can I remove the account because I did not personally receive the loan amount?
Not merely for that reason. If you genuinely provided the guarantee and the information is accurate, not receiving the loan proceeds does not automatically make the reporting incorrect.
5. What if I never signed or provided a guarantee?
If you do not recognise the borrowing or guarantee relationship, the account’s attribution and supporting information require examination. An inaccurate association may warrant correction through the applicable lender and credit bureau mechanisms.
6. What if my guarantor account is incorrectly shown as an individual borrowing?
The ownership classification should be examined against the actual loan and guarantee relationship. If a material reporting error is established, rectification may be appropriate.
My Perspective
In our customer case, the initial concern was understandable.
The customer remembered borrowing ₹5 lakh but saw a ₹50 lakh account in the credit information available to them.
A conclusion based only on those two amounts could have led to an incorrect allegation of inflated loan reporting.
The detailed examination revealed that the customer was associated with the larger facility as a guarantor.
This is precisely why I believe a Credit Report should never be interpreted from one amount alone.
A sanctioned amount tells us the size of a credit facility. It does not, by itself, tell us the individual’s relationship with that facility.
A borrower, joint borrower and guarantor should not be treated as interchangeable.
At the same time, a genuine guarantee does not excuse inaccurate ownership classification or other incorrect account information.
The objective of professional Credit Report analysis is to establish the actual credit relationship and identify whether the information accurately represents it.
Final Takeaway
If you borrowed ₹5 lakh but your CIBIL Report shows a ₹50 lakh account, do not immediately conclude that the lender has reported the wrong loan amount.
The larger facility may be connected with a genuine guarantee.
Remember:
Sanctioned Amount ≠ Current Balance.
Current Balance ≠ Amount Overdue.
Primary Borrower ≠ Guarantor.
And most importantly:
A genuine guarantee does not automatically mean every reported detail is accurate.
Understanding the complete account information is essential before determining whether Credit Rectification is required.
Professional Credit Report Assessment & Rectification
Does your CIBIL Report show a loan amount that you do not recognise?
Are you unsure whether an account reflects your personal borrowing, joint borrowing or a guarantee?
Apoorvaa provides professional Credit Report assessment and Credit Rectification for individuals and businesses where account ownership, guarantor status or other material credit information requires examination.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported information, an increase in any credit score or future loan approval.
Related Credit Education
- Loan Is Yours but Lender Name Is Different in CIBIL Report? Here’s Why
- Loan Closed but CIBIL Shows Outstanding Balance? Here’s Why
- Old Loan Suddenly Appeared in CIBIL Report After Years? Here’s What It Means
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed