

“My bank has written off my loan. Does that mean I no longer have to repay it?”
A customer recently raised this question after noticing “Written-Off” against a loan account in the CIBIL Report.
The customer believed that the bank had forgiven the loan. But when the customer applied for another loan, the application was rejected.
The confusion was understandable: if the bank has written off the account, why does the loan still matter?
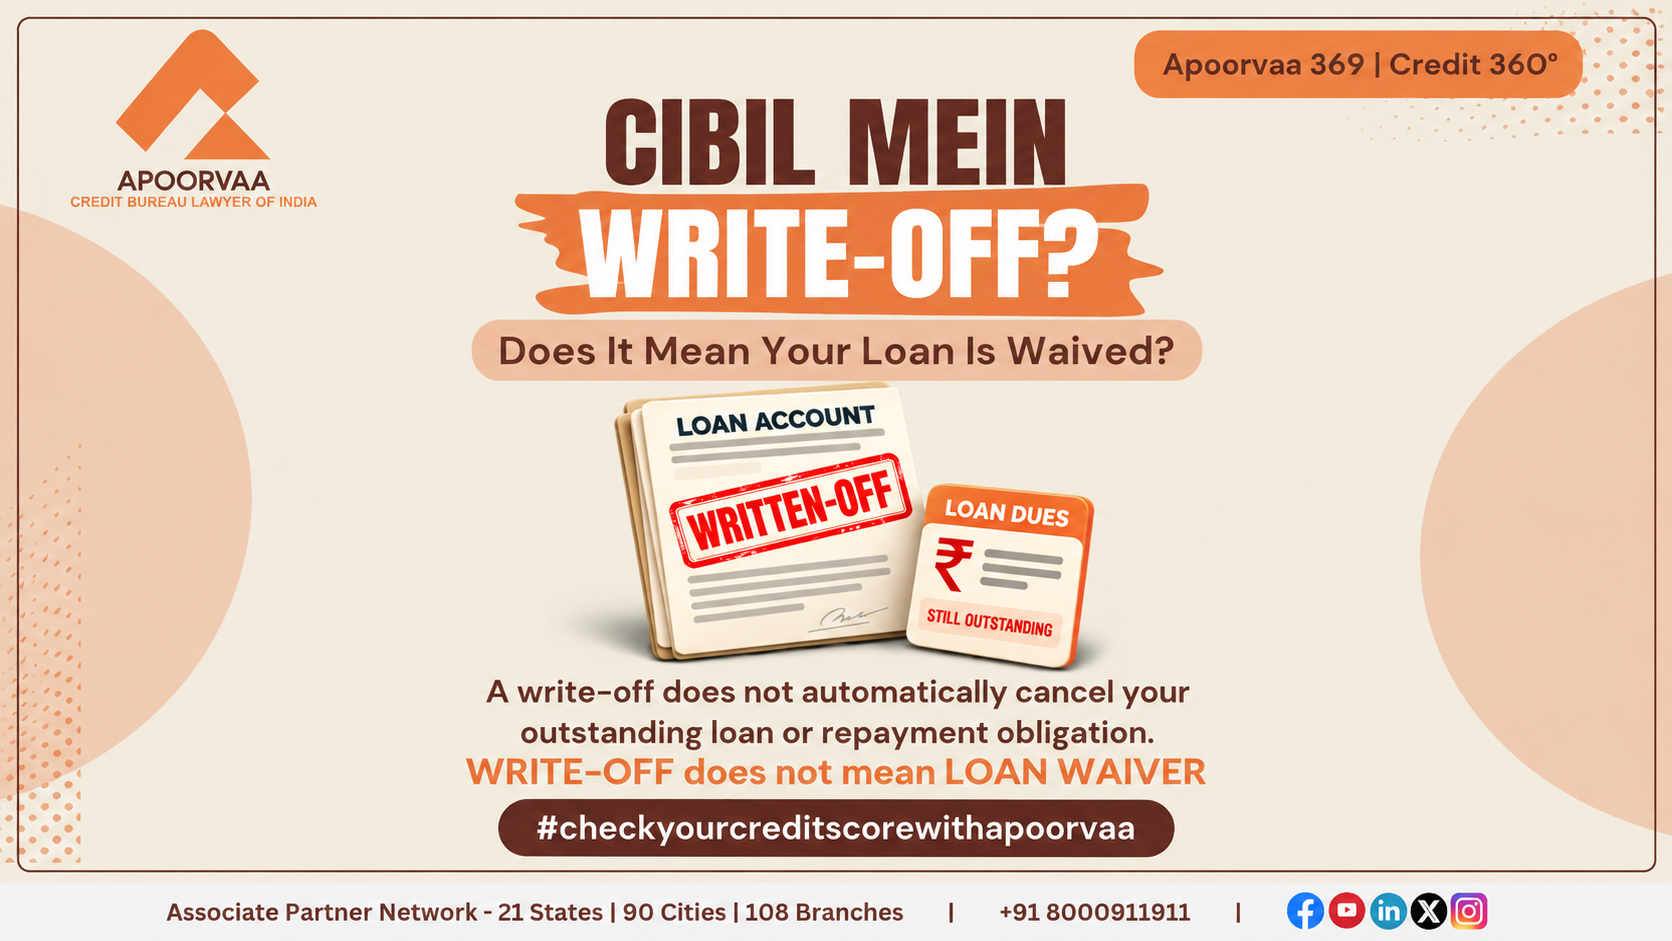
The answer is that a loan write-off is not the same as a loan waiver.
A write-off can be an accounting treatment adopted by a lender in relation to a stressed or non-performing loan. In a technical write-off, the lender does not give up its claim against the borrower merely because the amount has been written off for accounting purposes.
The Reserve Bank of India expressly distinguishes technical write-offs from arrangements involving a waiver of claims. Its June 8, 2023 Framework for Compromise Settlements and Technical Write-offs explains that a technical write-off may be full or partial, while the non-performing asset remains outstanding at the borrower’s loan-account level and recovery rights are preserved.
This distinction matters for two reasons.
First, a borrower should not assume that the repayment obligation has disappeared.
Second, the presence of Written-Off information in a CIBIL Report may remain relevant when another lender evaluates a fresh credit application.
Understanding the actual account position is therefore more important than interpreting the word “write-off” as a promise of loan forgiveness.
What Does Write-Off Mean in a CIBIL Report?
When a loan account is reported as Written-Off, it generally indicates that the lender has reported a write-off-related status associated with that credit facility.
The term should not be read as confirmation that the borrower has been released from repayment.
TransUnion CIBIL identifies Written-Off and Settled as distinct account-status information that lenders may consider while evaluating a credit application. Its guidance also encourages borrowers to examine account-level details rather than relying only on the three-digit CIBIL Score.
The meaning of the entry must be understood in the context of the underlying loan.
Relevant questions include whether the account remains outstanding, whether any amount has subsequently been recovered, whether a settlement or waiver has been agreed, and whether the reported information accurately reflects the lender’s records.
The central point is simple:
“Written-Off” does not, by itself, mean “Loan Waived.”
It also does not establish that the bank has abandoned recovery or that the account has no relevance to the borrower’s future credit profile.
What Is a Technical Write-Off Under RBI’s Framework?
The RBI’s June 8, 2023 framework provides an important regulatory explanation of technical write-offs.
Under that framework, a technical write-off concerns a non-performing asset that is written off fully or partially by a regulated entity for accounting purposes, while remaining outstanding at the borrower’s loan-account level.
The framework expressly states that this treatment does not involve a waiver of the lender’s claim and does not prejudice recovery of the amount.
This establishes a distinction between two different matters:
The lender’s accounting treatment of the loan
and
The borrower’s obligation under the underlying credit arrangement.
A bank may make an accounting decision about a stressed asset without agreeing to release the borrower from the debt.
That is why the expression “written off” should not be interpreted in isolation.
Why Does a Bank Write Off a Stressed Loan?
A bank may have a loan account on which repayment has become irregular or recovery is uncertain.
Such an account may be classified as a non-performing asset, subject to the applicable regulatory requirements.
Banks must account for stressed assets and make provisions in accordance with the relevant prudential framework.
A write-off can form part of the lender’s accounting treatment of that exposure.
In a 2016 clarification, RBI explained that writing off non-performing assets is a regular banking exercise associated with balance-sheet management. It specifically clarified that technical write-offs do not mean banks have surrendered their recovery rights.
For a borrower, the important point is that an accounting entry made by the lender does not automatically establish that the underlying loan obligation has been cancelled.
Loan Write-Off vs Loan Waiver vs Loan Settlement
These three expressions are often used interchangeably in everyday conversation.
They should not be.
Each describes a different concept, and confusing them can lead to incorrect assumptions about repayment obligations and credit-report information.
| Term | What it means | Does it automatically release the borrower from the entire debt? |
| Loan Write-Off | An accounting treatment relating to a loan or part of a loan. Under RBI’s technical write-off framework, the lender’s claim is preserved. | No. A technical write-off does not itself waive the lender’s claim. |
| Loan Waiver | A release from repayment of an amount under an applicable waiver arrangement or decision. | Only to the extent actually covered by the waiver and its terms. |
| Loan Settlement | An agreed arrangement to resolve the lender’s claims, potentially involving acceptance of less than the amount otherwise due. | Depends on the agreed terms and their fulfilment; it is not the same as a unilateral accounting write-off. |
RBI’s 2023 framework defines a compromise settlement as a negotiated arrangement with the borrower to settle the regulated entity’s claims in cash. Such an arrangement may involve the lender sacrificing part of the amount due and waiving its claim to that extent. RBI defines a technical write-off separately and expressly preserves the lender’s claim in that case.
Example: Write-Off Is Not Waiver
Suppose a borrower has an outstanding loan that becomes non-performing.
The lender subsequently undertakes a technical write-off.
The borrower sees Written-Off in the CIBIL Report and concludes:
“The bank has removed the loan from its books, so I no longer owe anything.”
That conclusion does not follow.
The lender’s accounting treatment and the borrower’s liability are separate questions.
The actual amount due, any subsequent recovery, and any agreed resolution must be understood from the relevant account and contractual records.
Example: Settlement Is Not the Same as Write-Off
Now consider a different situation.
A borrower and lender enter into an agreed settlement under which the borrower is required to pay a specified amount to resolve the lender’s claims on agreed terms.
That arrangement should be assessed according to the settlement terms and the actual payments made.
It should not be confused with a technical write-off undertaken by the lender for accounting purposes.
A borrower should never assume that the words “write-off,” “waiver” and “settlement” establish the same legal or financial position.
Can a Bank Continue Recovery After Writing Off a Loan?
Yes. A technical write-off does not, by itself, prevent the lender from continuing recovery.
This is one of the most important aspects of RBI’s framework.
The RBI definition expressly preserves the lender’s claim against the borrower in a technical write-off and states that the accounting treatment is without prejudice to recovery.
A borrower should therefore not assume:
- The bank has forgiven the loan.
- The bank has lost its right to seek repayment.
- Recovery activity must automatically stop.
- Any existing legal proceedings must automatically end.
Whether a particular recovery measure is available or appropriate depends on the underlying contract, applicable law, account circumstances and any subsequent settlement, waiver or other legally effective arrangement.
The write-off entry alone does not answer all those questions.
Accounting treatment does not automatically cancel a legal claim.
This is why customers should understand the actual account position instead of relying solely on a status label in the CIBIL Report.
Does Every Loan Write-Off Have Exactly the Same Meaning?
No.
The term “write-off” may be encountered in different accounting, regulatory and credit-reporting contexts.
RBI’s technical write-off definition is particularly important because it expressly distinguishes the lender’s accounting treatment from waiver of its claim.
However, the precise position of a particular account may also depend on whether the write-off was full or partial, whether recovery occurred later, and whether the parties subsequently entered into a settlement or another arrangement.
A borrower should not infer the complete legal and financial position from one word in the Credit Report.
The account status, outstanding amount, repayment history and underlying lender records need to be interpreted together.
This becomes especially important when a customer says:
“My account is written off, but the bank is still asking me to pay.”
Those two facts are not necessarily inconsistent.
Why Does Written-Off Status Matter When You Apply for Another Loan?
A borrower may assume that a written-off account is no longer relevant because the original lender has already made an accounting adjustment.
But another lender may consider the reported history when assessing a fresh application.
TransUnion CIBIL explains that lenders do not view written-off and settled account statuses favourably when evaluating credit applications.
This does not mean every lender must automatically reject every borrower with a written-off account.
A lending decision may also involve income, repayment capacity, existing obligations, the complete Credit Report and the lender’s own credit policy.
However, written-off information can raise questions about the repayment history associated with the earlier facility.
For example, a new lender may want to understand:
Was the earlier loan repaid as agreed?
Does an outstanding amount remain?
Was there a subsequent recovery or settlement?
Does the current Credit Report accurately reflect the account’s position?
These are materially different questions from whether the bank has already written off an amount in its accounting records.
Does Written-Off Status Automatically Mean Your Next Loan Will Be Rejected?
No.
A written-off account may be an important adverse factor in credit assessment, but it does not establish a universal rule that every lender must reject the application.
Lenders make credit decisions according to their own assessment and applicable requirements.
A borrower may have other relevant information in the credit profile, including subsequent repayment history and current financial circumstances.
Nevertheless, it would be equally incorrect to dismiss a written-off entry as harmless merely because the bank has already accounted for the stressed asset.
A written-off account deserves attention because it may remain relevant to the borrower’s credit history and the lender’s assessment of repayment risk.
That is why understanding the status before submitting another loan application matters.
Why Checking Only Your CIBIL Score Is Not Enough
A customer may have a CIBIL Score and still misunderstand what is appearing against a particular loan account.
The Score is a summary measure.
It does not replace the account-level information contained in the complete Credit Report.
For a written-off facility, the account details may provide important context about the reported status, outstanding balance, repayment history and the date on which information was last reported.
TransUnion CIBIL’s guidance specifically directs readers to examine account details and account status when interpreting their Credit Report.
The practical lesson is that a borrower should not conclude:
“My Score has changed, so the write-off must have disappeared.”
Nor should a borrower conclude:
“The bank wrote off the loan, so the account no longer matters.”
The complete Credit Report and the actual lender records need to be understood together.
What If I Have Already Repaid a Written-Off Loan?
A customer may raise a different question after understanding the meaning of a write-off:
“My loan was written off earlier, but I have now repaid the bank. Why is Written-Off still appearing in my CIBIL Report?”
This situation requires careful interpretation.
A loan’s historical write-off, subsequent repayment and present outstanding balance are three separate matters.
If the lender undertook a technical write-off when the account was non-performing, a later repayment does not mean the earlier accounting event never occurred.
However, the Credit Report should accurately reflect the subsequent developments in the account.
For example, if the customer has fully discharged the amount legally payable under the relevant arrangement, an outstanding balance that continues to be reported without reflecting that payment may require examination.
At the same time, the customer should not assume that making a payment automatically requires every historical reference to the write-off to disappear.
Repayment after write-off does not automatically erase the historical account status.
The relevant questions are whether the current account information is accurate, whether the repayment has been appropriately reflected and whether the reported status is consistent with the actual account position.
Does Paying a Written-Off Loan Automatically Remove the Written-Off Status?
No. Repayment does not guarantee automatic deletion of the historical Written-Off status.
This is an important distinction because customers sometimes expect their Credit Report to become completely free of adverse history immediately after making a payment.
Consider a loan that became non-performing and was subsequently written off.
The customer later pays the outstanding dues.
The subsequent repayment is an important development, but it does not necessarily make the earlier write-off historically inaccurate.
The lender’s current reporting should be assessed in light of the actual repayment and account records.
A customer should therefore distinguish between:
Correcting the present account position
and
Removing accurately reported historical credit information.
These are not the same objective.
TransUnion CIBIL explains that account information is supplied by credit institutions and that CIBIL cannot independently modify it without confirmation from the relevant institution.
This is why a customer should not rely on promises that every written-off entry can be deleted merely by making a payment.
Written-Off Amount, Current Balance and Amount Overdue: Why the Difference Matters
A CIBIL Report may contain several fields relating to a loan account.
For a written-off facility, customers should not interpret each field as though it describes the same thing.
The historical write-off amount, current balance and amount overdue may convey different information.
| Credit-report information | What it helps explain |
| Written-Off Status | The reported account status associated with the earlier write-off |
| Written-Off Amount | The amount reported in connection with the write-off, where applicable |
| Current Balance | The balance currently reported against the account |
| Amount Overdue | The amount reported as overdue |
| Date Reported | When the lender last reported the relevant account information to the credit bureau |
The meaning of these fields must be assessed together with the actual lender records.
For example, a historical written-off amount should not automatically be treated as proof that the same amount remains payable today.
Conversely, a zero current balance does not automatically establish that the earlier write-off never occurred.
The customer may have repaid the account, entered into a settlement, received a waiver covering an amount, or experienced another subsequent account development.
Each situation can have different implications.
TransUnion CIBIL’s guidance identifies account status, balances, account details and reporting dates as relevant information when reading a Credit Report.
A single field should not be interpreted without understanding the complete account history.
What If My Current Balance Still Shows an Amount After Repayment?
Suppose a customer repays a written-off loan but continues to see an outstanding amount in the CIBIL Report.
The customer may immediately conclude that the lender has failed to update the account.
That may be a possibility, but it should not be assumed without understanding the facts.
Several questions become relevant.
Was the payment intended to discharge the entire amount payable?
Was it a partial repayment?
Was the payment made under an agreed settlement?
Did any amount remain payable under the applicable arrangement?
Has the lender reported the subsequent account development?
A payment receipt alone may establish that a payment occurred, but it does not necessarily establish that every amount claimed under the account has been discharged.
Equally, where the account has been fully resolved, the continued reporting of an inconsistent current balance may require attention.
The correct reporting position depends on what actually happened to the loan account.
This is where accurate account interpretation becomes more important than simply requesting removal of the Written-Off label.
Written-Off After Full Repayment vs Written-Off After Settlement
Two customers may both say:
“I have paid the bank, but my CIBIL Report still shows Written-Off.”
Yet their underlying situations may be different.
Situation 1: Repayment of the Full Amount Payable
The customer may have paid the amount required to fully discharge the loan obligation.
The subsequent account information should be assessed against that repayment and the lender’s records.
Whether the historical write-off remains reportable is a separate question from whether the current balance and other account details accurately reflect the repayment.
Situation 2: Payment Under a Compromise Settlement
The customer may have entered into an agreed settlement under which the lender accepted a specified amount to resolve its claims.
That arrangement is not the same as full repayment of the original contractual amount.
Under RBI’s June 8, 2023 framework, a compromise settlement may involve the lender accepting a negotiated amount and waiving its claim to the extent agreed. A technical write-off, by contrast, does not itself waive the lender’s claim.
The reporting position must therefore be assessed according to the actual arrangement.
Payment after a write-off does not automatically establish whether the account was fully repaid, settled or resolved under another arrangement.
Can a Bank Continue Recovery After Partial Repayment of a Written-Off Loan?
A partial repayment does not necessarily extinguish the entire outstanding obligation.
If the customer pays only part of the amount claimed, the remaining position depends on the underlying credit agreement, the actual amount payable and any subsequent legally effective arrangement.
For example, the lender may have agreed to accept a specified settlement amount in full resolution of its claims.
Alternatively, the customer may simply have made a payment towards an existing outstanding amount without entering into such an arrangement.
These are different situations.
A technical write-off does not, by itself, prevent recovery of the lender’s claim. RBI’s framework expressly preserves recovery rights in relation to technically written-off accounts.
However, the availability of a particular recovery action must still be assessed under the applicable law and the specific account circumstances.
The word “Written-Off” alone cannot establish how much remains legally payable or which recovery measures are available.
Genuine Written-Off History vs Incorrect or Outdated Reporting
This distinction is central to responsible Credit Rectification.
A customer may have a genuine written-off loan account.
The customer may also have inaccurate information appearing against that same account.
These two possibilities are not mutually exclusive.
Consider the following examples.
Example 1: Accurately Reported Historical Write-Off
A loan became non-performing and was genuinely written off.
The Credit Report accurately reflects the relevant historical event.
The customer is concerned that the entry may affect a fresh loan application.
However, the potential effect on loan eligibility does not automatically make the historical information inaccurate.
Example 2: Outstanding Balance Inconsistent With Subsequent Repayment
A loan was written off.
The customer subsequently made payments that should be reflected in the account’s present position.
The Credit Report continues to show information that appears inconsistent with the lender’s records.
The concern may involve the accuracy of the current reporting rather than whether the earlier write-off occurred.
Example 3: Incorrect Account Status
A customer finds a write-off-related status that appears inconsistent with the actual account history.
The underlying lender records and reported information may need to be examined to understand the discrepancy.
Example 4: Unrecognized Written-Off Account
A customer finds a written-off facility that they do not recognize.
The relevant question is whether the account genuinely relates to the customer, including any actual borrower, joint-borrower or guarantor relationship.
An unfamiliar account should not automatically be assumed fraudulent or incorrectly reported without understanding the underlying facts.
The objective is to distinguish accurately reported adverse history from genuinely inaccurate credit information.
Credit Rectification should not be presented as a method for making every unfavourable account disappear.
Can Written-Off Status Be Corrected in a CIBIL Report?
A genuinely inaccurate or outdated entry may require correction, but the appropriate reporting outcome depends on the underlying facts.
A customer may have grounds to question account information that does not accurately reflect the lender’s records or subsequent developments.
However, the existence of a write-off does not itself establish a reporting error.
Nor does the customer’s payment automatically establish that all historical write-off information must be deleted.
TransUnion CIBIL explains that the relevant credit institution must confirm changes to account information before CIBIL can modify the reported record.
This is why a professional assessment should focus on identifying the actual discrepancy rather than promising a predetermined change in account status.
Will Correcting a Written-Off Account Guarantee Loan Approval?
No.
A written-off account may be relevant to a lender’s assessment, but correcting inaccurate information does not guarantee approval of the next application.
A lender may also consider:
- The customer’s broader repayment history
- Existing credit obligations
- Income and repayment capacity
- The amount and type of loan requested
- Its own credit and eligibility policies
Even where a genuine reporting discrepancy is corrected, the lender retains responsibility for its credit decision.
Likewise, a customer should not assume that a written-off account means every future application must be rejected.
Credit-report accuracy and loan eligibility are related, but they are not identical.
Frequently Asked Questions
1. Does Written-Off in CIBIL mean my loan is waived?
No. A technical write-off is an accounting treatment and does not itself waive the lender’s claim against the borrower.
2. Can a bank recover money after writing off a loan?
Yes. A technical write-off does not itself prevent recovery. The availability of specific recovery measures depends on the applicable law and account circumstances.
3. Does Written-Off mean the bank has closed my loan?
Not necessarily. A write-off should not be confused with repayment, closure, waiver or settlement. The actual account position must be understood separately.
4. What happens if I repay a written-off loan?
The subsequent repayment is relevant to the account’s current position. However, repayment does not automatically erase accurately reported historical write-off information.
5. Why does my CIBIL Report still show Written-Off after payment?
The historical write-off and subsequent repayment are separate matters. The report needs to be assessed to determine whether the present status and balances accurately reflect the actual account history.
6. Does a zero current balance mean the write-off was removed?
No. A zero current balance and historical write-off information describe different aspects of the account.
7. Is a write-off the same as a settlement?
No. A technical write-off is an accounting treatment that preserves the lender’s claim. A compromise settlement is a negotiated arrangement to resolve claims according to agreed terms.
8. Can a written-off loan affect future loan applications?
Yes. Lenders may consider written-off information during credit assessment. However, it does not establish that every lender must automatically reject the borrower.
9. Can I remove a genuine write-off from CIBIL after repayment?
Repayment does not guarantee automatic deletion of accurate historical information. Potentially inaccurate reporting requires separate assessment.
10. When is professional Credit Rectification relevant?
Professional assessment may be relevant when the reported status, balance, account relationship or other information appears inaccurate, inconsistent or outdated in light of the actual account records.
My Perspective
When a customer tells me, “My bank has written off my loan, so why should I repay it?”, the first issue is the meaning of the word write-off.
A technical write-off is not a promise of loan forgiveness.
It is important to understand the lender’s accounting treatment, the borrower’s actual obligation and the information reported to the credit bureau as separate matters.
I also see another type of confusion.
A customer repays a previously written-off loan and assumes that the historical write-off must immediately disappear from the CIBIL Report.
But repayment and historical reporting are different questions.
The current balance may need to reflect the subsequent repayment, while the earlier write-off may remain part of the accurately reported account history.
For me, the central question is not simply:
“How can Written-Off be removed from CIBIL?”
It is:
“Does the complete Credit Report accurately reflect what actually happened to this loan account?”
That distinction is essential for responsible Credit Rectification.
Final Thought
Write-off does not mean loan waiver.
A bank’s technical write-off does not automatically cancel the borrower’s repayment obligation or prevent recovery.
Written-off information may also remain relevant when the borrower applies for fresh credit.
If the customer subsequently repays the loan, the current account information should be understood alongside the historical write-off.
An inaccurate balance or status may require attention, but accurately reported adverse history should not automatically be described as an error.
Understand the loan account before assuming the bank has forgiven the debt—or that every written-off entry can be deleted after payment.
Professional Credit Report Assessment
If your CIBIL Report contains a Written-Off account, it is important to understand the actual account position before applying for another loan.
Where the reported status, outstanding balance, repayment information or other account details appear inconsistent with the lender’s records, professional assessment can help identify whether a genuine Credit Rectification concern exists.
Apoorvaa – Credit Bureau Lawyer of India provides professional Credit Report assessment and Credit Rectification services for individuals and businesses.
📞 +91 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported write-off history, a particular CIBIL Score or loan approval. Repayment obligations and recovery rights depend on the applicable law, account records and any legally effective settlement or waiver.
Related Credit Education
- Outstanding Bank Dues: Can CIBIL Be Fixed Without Payment?
- Write-Off Account Payment: Avoid This Costly Mistake
- Does Loan Rejection Affect Your CIBIL Score? Understanding Hard Enquiries and Repeated Applications
About the Author
Advocate Apurva Bhagat is the Founder & Chairman of Apoorvaa – Credit Bureau Lawyer of India.
His work focuses on credit-bureau law, Credit Rectification and helping individuals and businesses understand the difference between genuine credit obligations, inaccurate credit reporting and lender-specific credit decisions.

Comments are closed