

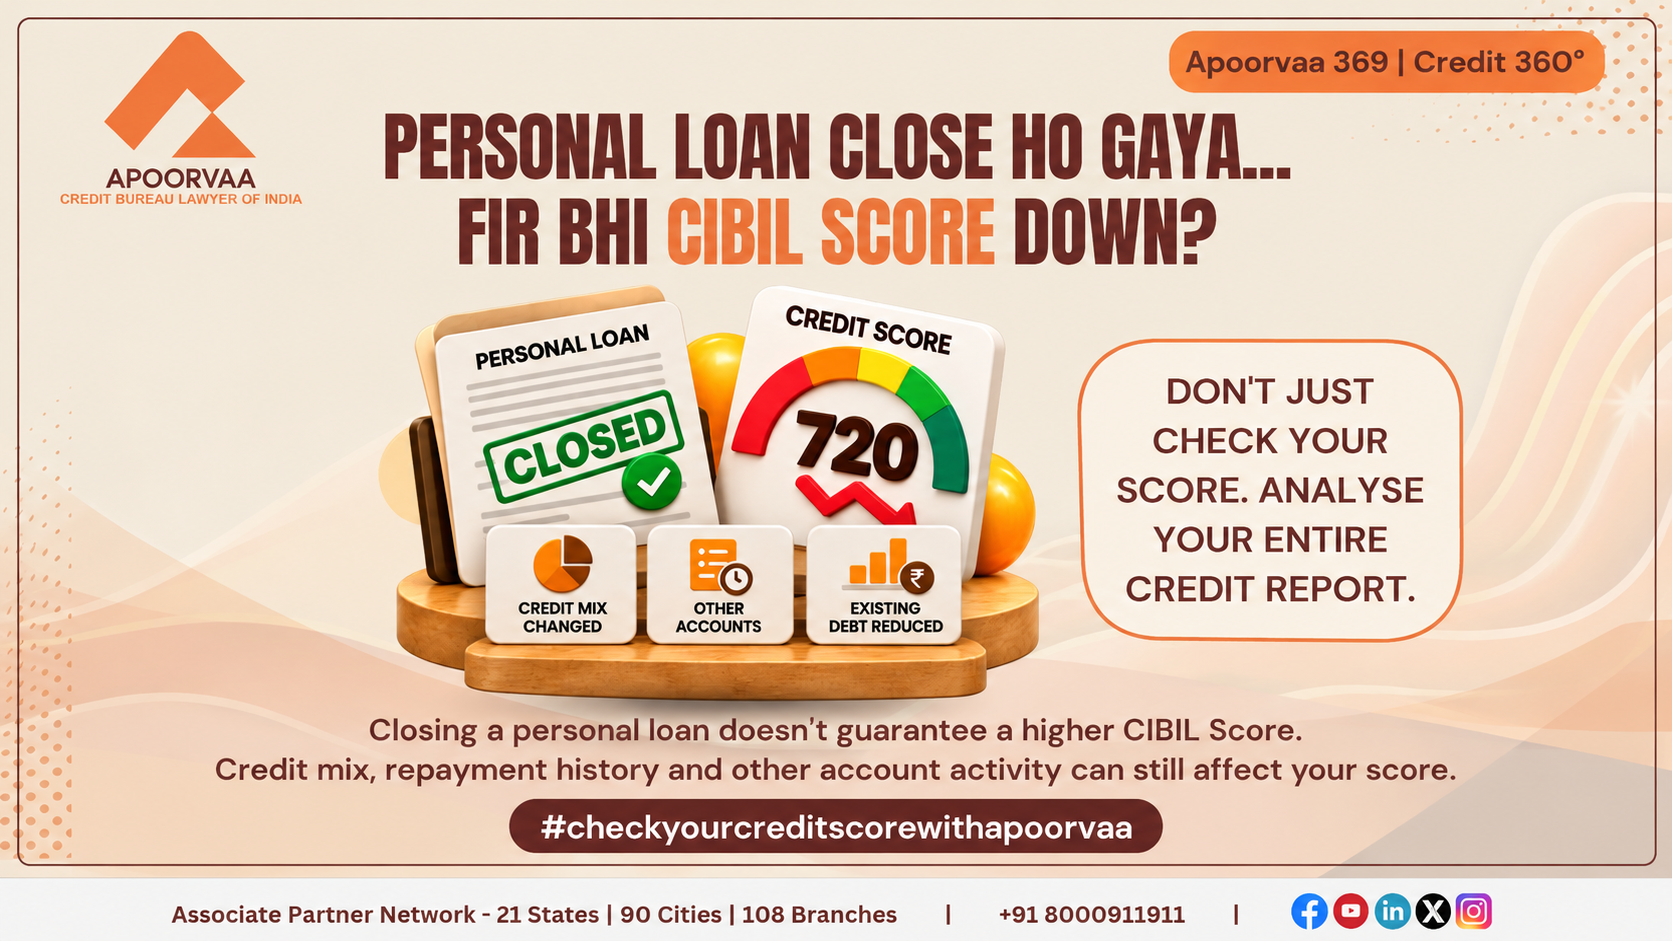
“I have completely repaid my personal loan, so why is my CIBIL Score still decreasing?”
This is a common concern among borrowers who have successfully repaid their personal loans.
A borrower clears the final EMI, completes the loan and expects the CIBIL Score to increase. Instead, the score decreases.
Does this mean closing the personal loan negatively affected the credit score?
Not necessarily.
Repaying a loan is a positive financial action, but a CIBIL Score is calculated using multiple aspects of a borrower’s credit history. A score decline following loan closure does not automatically establish that the closure caused it.
Understanding the difference between loan repayment, account closure and overall credit-profile changes is essential.
1. Why Did My CIBIL Score Drop After Closing a Personal Loan?
A CIBIL Score reflects information from the consumer’s overall credit profile, not the status of one loan alone.
TransUnion CIBIL identifies factors such as payment history, credit utilisation, credit history and enquiries as relevant to scoring.
When a personal loan is closed, the borrower’s credit information changes. However, other accounts may also have been updated during the same period.
For example, a consumer may close a personal loan while simultaneously experiencing higher credit-card utilisation or a newly reported overdue payment on another account.
The resulting score movement cannot automatically be attributed to the closed personal loan.
Loan Closed ≠ Guaranteed Score Increase
2. Does Repaying a Personal Loan Automatically Increase Your CIBIL Score?
No.
Full repayment reduces the borrower’s outstanding debt and completes an important financial obligation.
However, credit scoring does not operate on a simple rule where closing one loan automatically adds points.
The score may increase, decrease or remain relatively stable depending on the information considered by the scoring model.
The precise calculation used by TransUnion CIBIL is proprietary, so an individual score movement cannot always be attributed conclusively to one account-level change.
Importantly, a declining score does not automatically mean the lender has reported incorrect information.
3. What Changes in Your Credit Profile When a Loan Closes?
Closing a personal loan can change several aspects of the credit report.
| Credit-profile element | Possible change |
| Account Status | Loan moves from active to closed |
| Current Balance | Outstanding balance becomes zero following full repayment |
| Active Accounts | Number of active loan accounts decreases |
| Outstanding Debt | Total outstanding obligations reduce |
| Credit Mix | Composition of active credit facilities may change |
These changes are not inherently negative.
For example, reducing outstanding debt is financially beneficial, even if the CIBIL Score does not immediately rise.
A closed personal loan may also remain visible as part of the consumer’s historical credit information.
Loan closure does not mean the account’s repayment history disappears.
4. Can Credit Mix Affect Your CIBIL Score?
Credit mix refers to the composition of credit facilities in a borrower’s profile, including secured and unsecured credit.
A personal loan is generally an unsecured instalment loan.
When it closes, the composition of active credit accounts may change.
Credit mix can be relevant to scoring, but a change in credit mix does not automatically mean the score must decrease.
Its significance depends on the overall credit history and other account information.
It would therefore be misleading to suggest that closing a personal loan is inherently harmful to a borrower’s credit score.
5. Other Credit Accounts May Explain the Score Movement
Before linking a score decline to personal loan closure, other developments deserve attention.
These may include:
- Credit-card utilisation: Higher outstanding balances relative to revolving credit limits.
- Repayment delays: Recently reported overdue amounts or missed payments on other accounts.
- New credit enquiries: Recent applications for loans or credit cards.
- Newly reported accounts: Additional credit facilities appearing in the report.
- Changes in existing facilities: Updated balances, account information or repayment history.
For example, a borrower may fully repay a personal loan but have a separate credit-card account reporting a missed payment.
The credit-card information may influence the overall profile independently of the loan closure.
Credit-card utilisation should also not be confused with the repayment progress of a personal loan. These credit facilities operate differently.
The central question is not simply whether a loan was closed, but what changed across the entire credit report during the relevant period.
6. Full Personal Loan Closure vs Settlement: Why the Difference Matters
Full repayment and settlement are not the same.
Full repayment and closure generally mean the borrower has paid the entire amount due and the lender has completed the loan closure.
Settlement generally means the lender has accepted an agreed amount that may be lower than the total amount payable.
A settled account can carry different implications for credit assessment than a fully repaid and closed account.
Therefore, when examining a score decline, it is important to establish whether the loan was correctly reported as closed or settled.
7. What If the Bank Has Not Updated the Loan Closure?
A borrower may complete the final payment, but the CIBIL Report may still reflect the loan’s earlier status.
This can occur because credit reporting is not instantaneous.
Under RBI’s credit-information reporting framework, lenders are required to update credit information on a fortnightly basis, subject to prescribed submission and processing timelines.
The relevant reporting dates are the 15th and last day of each month, or shorter intervals where agreed.
Consequently, a recently repaid loan may not immediately appear as closed in the latest report.
However, if the lender has confirmed closure and the account continues to show inaccurate information beyond the applicable reporting period, further examination may be necessary.
Reporting Delay ≠ Incorrect Reporting
A loan correctly reported as closed may continue to appear in the CIBIL Report as historical credit information.
Its continued visibility alone is not an error.
8. How Should a Falling CIBIL Score Be Interpreted?
A useful approach is to compare the current credit report with an earlier report.
The comparison should focus on material changes, including:
- Loan closure and outstanding balances.
- Repayment history across other accounts.
- Credit-card balances and utilisation.
- Recently reported credit enquiries or new accounts.
- Account information that appears inconsistent with lender records.
This may help identify developments that could have contributed to the score movement.
However, identifying a change does not necessarily prove that it caused a particular score decrease.
The precise contribution of each factor may not be determinable because the scoring calculation is proprietary.
A falling score should therefore be examined in context rather than automatically treated as a credit-reporting error.
9. When Is Professional Credit Report Analysis Appropriate?
Professional analysis becomes relevant when the borrower cannot understand the changes in the credit profile or suspects that information has been inaccurately reported.
For example, the lender may have confirmed full loan closure while the credit report continues to show an incorrect outstanding balance or account status.
Such discrepancies require assessment against the lender’s records and applicable reporting dates.
At Apoorvaa, professional Credit Report analysis focuses on understanding account-level information, identifying potential contributing factors and evaluating genuine Credit Rectification requirements.
A score decline alone is not sufficient evidence that rectification is necessary.
Frequently Asked Questions
Will my CIBIL Score increase after closing a personal loan?
Not necessarily. Loan closure does not guarantee an immediate or continuous score increase.
Can a closed personal loan remain visible in CIBIL?
Yes. Accurate historical account information may remain in the report after closure.
Does a falling score mean the bank reported something incorrectly?
No. Score movements may occur even when the reported information is accurate.
Can correcting a loan-closure reporting error improve my score?
Correction ensures more accurate credit information, but a specific score increase cannot be guaranteed.
My Perspective
In my professional experience, borrowers often expect their CIBIL Score to rise immediately after repaying a personal loan.
However, loan repayment is a financial event, while a credit score reflects the broader credit profile.
The two should not be interpreted as a direct cause-and-effect relationship.
I believe the correct approach is to examine what has changed in the credit report and whether those changes accurately reflect the borrower’s accounts.
Credit Rectification should address genuine inaccuracies—not ordinary score fluctuations.
Final Takeaway
If your CIBIL Score dropped after personal loan closure, do not immediately assume that closing the loan caused the decline.
Other credit accounts, repayment behaviour, credit utilisation and reporting updates may also be relevant.
LOAN CLOSED ≠ GUARANTEED SCORE INCREASE
UNDERSTAND YOUR COMPLETE CREDIT REPORT, NOT JUST YOUR SCORE.
Has Your CIBIL Score Dropped After Loan Closure?
If you have fully repaid your personal loan but cannot understand the changes in your CIBIL Report, Apoorvaa offers professional Credit Report analysis.
Our services help evaluate account-level information, identify genuine discrepancies and assess whether Credit Rectification is appropriate.
Purchase your Credit Report and get it professionally analysed by Apoorvaa.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Report analysis and rectification do not guarantee a specific score increase or loan approval.
Related Credit Education
- Wrong Credit Card Limit in CIBIL Report: Does It Affect Your Score?
- CIBIL Current Balance Zero: Does It Mean Your Credit Card Is Closed?
- Old Loan Suddenly Appeared in CIBIL Report After Years? Here’s What It Means
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed