

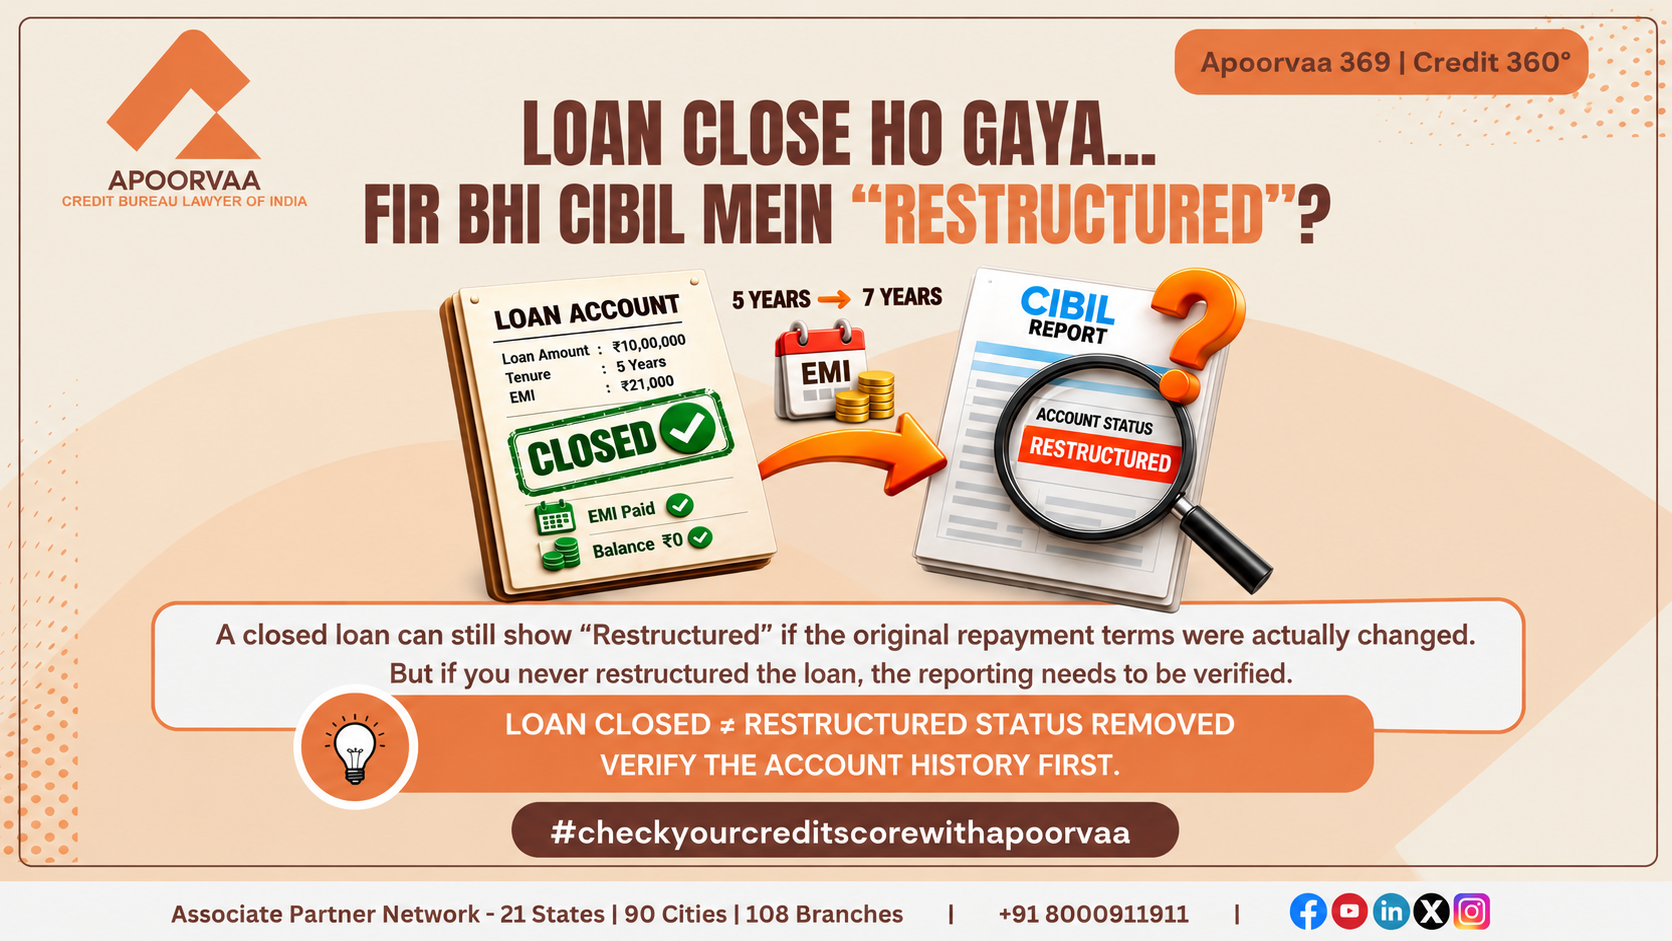
“My loan is fully repaid and closed. Why does my CIBIL Report still show Restructured?”
This question creates understandable confusion.
Imagine that you took a five-year loan. At some point during the loan, its original repayment arrangement was modified. Later, you paid every amount required under the revised arrangement, completed the loan and obtained closure documents from the lender.
Today, there may be no outstanding balance.
Yet when you examine your CIBIL Report, you find a restructuring-related classification against that account.
Does this automatically mean the lender has reported the loan incorrectly?
No.
But neither should every restructuring classification be assumed to be correct without examining the underlying records.
The first distinction to understand is this:
Loan closure describes the present position of the credit facility. Restructuring describes an event that may have occurred during the life of that facility.
The two pieces of information can therefore be relevant to the same loan.
The real question is whether the restructuring classification accurately reflects what actually happened to the account.
1. What Exactly Does Loan Restructuring Mean?
Loan restructuring should not be reduced to a simple statement such as “the EMI changed” or “the tenure increased.”
Under the Reserve Bank of India’s prudential framework, restructuring broadly concerns a situation where a lender, for economic or legal reasons connected with the borrower’s financial difficulty, grants concessions to the borrower.
Depending on the circumstances and applicable framework, restructuring can involve modification of the original terms of the credit facility, including matters such as:
- the repayment period,
- the amount payable,
- the amount of instalments,
- the rate of interest,
- rollover of certain credit facilities,
- additional credit or funds in specified circumstances, or
- other changes forming part of the restructuring arrangement.
The regulatory context is important.
A change in a loan term does not become “restructuring” merely because something in the loan changed.
For example, certain interest-rate or repayment-tenor changes arising under the original contractual structure or applicable regulatory framework may need to be distinguished from a concession granted because of the borrower’s financial difficulty.
Therefore:
Changed EMI ≠ automatically restructured.
Changed interest rate ≠ automatically restructured.
Extended tenure ≠ automatically proof of restructuring without understanding why and how the change occurred.
The underlying reason, documentation, applicable terms and lender records matter.
2. Is an EMI Bounce Necessary Before a Loan Can Be Restructured?
No.
This is an important misconception.
A borrower does not necessarily need to have already missed an EMI before financial difficulty can be identified for restructuring purposes.
Financial stress may be recognised before an actual default in appropriate circumstances.
For example, a lender may determine that the borrower is unlikely to continue servicing the facility under its existing contractual terms without a concession.
Therefore, statements such as:
“My EMI never bounced, so my loan could never have been restructured”
should not be treated as universally correct.
At the same time, an EMI bounce by itself does not prove that a loan was restructured.
A delayed payment and a formal restructuring of contractual terms are different matters.
This is why the account documentation becomes important.
3. Can a Closed Loan Still Show Restructured?
Yes, depending on the actual history of the account.
Consider a simplified example.
A borrower originally receives a loan repayable over five years.
Later, because of financial difficulty, the lender and borrower enter into a restructuring arrangement under which the repayment terms are modified.
The borrower subsequently follows the revised repayment arrangement, completes all required payments and the loan is ultimately closed.
Two facts can then coexist:
Fact 1: The loan is now closed.
Fact 2: The loan was restructured during its lifetime.
The second fact does not automatically become untrue because the first one happened later.
TransUnion CIBIL’s consumer material recognises restructuring-related classifications, including “Restructured Loan” and “Restructured Loan (Govt Mandated).”
Therefore, when a borrower sees restructuring-related information against an account that has subsequently been closed, the correct question is not simply:
“Why is this showing when my loan is closed?”
The better question is:
“Was my loan actually restructured, and does the information reported by the lender accurately represent that event?”
That distinction changes the entire analysis.
4. Restructured vs Closed: Why Both Can Be Relevant
Borrowers often treat “Closed” and “Restructured” as competing descriptions.
They may actually describe different dimensions of the credit facility.
Closed
Closure generally concerns the current lifecycle position of the account: the credit facility has ended and the lender has reported the applicable closure information.
Restructured
A restructuring-related classification concerns an event in the account’s history: the original credit arrangement was restructured under the applicable circumstances.
Accordingly, successful repayment after restructuring does not automatically establish that the restructuring never occurred.
For example:
Original loan → Financial difficulty → Restructuring → Revised repayment → Full repayment → Loan closure
At the end of this sequence, the borrower may legitimately say:
“I have completely repaid my loan.”
But that statement does not erase the earlier restructuring event.
This is similar to an important principle in credit-information analysis:
Present account position and historical account information should not be treated as the same thing.
The accuracy of each field or classification has to be examined according to what it represents.
5. Does Full Repayment Remove an Accurate Restructuring History?
Not automatically.
Suppose a borrower genuinely entered into a restructuring arrangement and subsequently paid every instalment according to the revised terms.
That is a positive development in the account’s later repayment history.
But repayment under the revised arrangement does not mean that the original restructuring event never occurred.
Therefore, professional Credit Rectification should not be presented as a mechanism for deleting a legitimate restructuring history simply because the loan has now been successfully repaid.
The objective must be accuracy.
If the information accurately reflects the account history, the fact that it may be viewed unfavourably by a future lender does not by itself make the information incorrect.
On the other hand, if the borrower never underwent a restructuring and the lender’s own records do not support the reported classification, that is a materially different situation.
6. What If I Never Restructured the Loan?
Now consider the opposite scenario.
A borrower says:
- I never requested restructuring.
- I never agreed to revised repayment terms because of financial difficulty.
- I continued paying according to my applicable loan arrangement.
- I have my sanction and repayment documents.
- The loan has subsequently been fully repaid and closed.
Yet the CIBIL Report shows a restructuring-related classification.
In such a situation, the classification should not simply be accepted or rejected based on the borrower’s recollection alone.
The underlying records need to be compared.
Depending on the case, relevant records may include:
Original sanction letter: What were the original contractual terms?
Restructuring letter or agreement: Was a formal restructuring arrangement actually approved or accepted?
Repayment history: How did the actual repayment pattern correspond with the original and any revised terms?
Loan statements: Were the contractual repayment obligations modified during the account?
Closure letter or NOC: What does the lender state about the eventual closure?
Complete Credit Report: What exactly has been reported, in which field, and alongside what other account information?
This comparison matters because an ordinary contractual adjustment should not automatically be confused with restructuring, while a genuine restructuring event should not be ignored merely because the loan was later paid in full.
The analysis must establish what actually happened.
7. Can an Incorrect Restructured Status Be Corrected?
Yes. If a restructuring-related classification is established to be inaccurate, the credit information can be taken up for correction through the applicable lender and Credit Information Company framework.
But there is an important distinction.
An unfavourable credit-history entry is not necessarily an inaccurate entry.
If the borrower genuinely underwent restructuring and the lender has accurately reported that event, subsequent repayment and closure of the loan do not automatically make the historical restructuring information incorrect.
Credit Rectification should therefore focus on correcting information that does not accurately reflect the underlying account records.
For example, further examination may be appropriate where:
- The borrower never requested or agreed to restructuring.
- The lender’s records do not support a restructuring event.
- The reported classification does not correspond with the documented loan history.
- The borrower believes an ordinary contractual or regulatory change has been incorrectly treated as restructuring.
- Different account records contain materially inconsistent information.
The question should always be:
Does the restructuring classification accurately represent what happened to this particular loan?
If yes, professional rectification should not be represented as a way to erase legitimate credit history.
If no, the discrepancy may require correction.
8. How Does the Lender and CIC Correction Framework Work?
Credit Institutions and Credit Information Companies have different roles in India’s credit-information system.
The bank, NBFC or other Credit Institution reports account information to Credit Information Companies such as TransUnion CIBIL.
Therefore, where a borrower disputes a restructuring-related classification, the underlying lender records become important.
A Credit Information Company provides mechanisms through which consumers can dispute information appearing in their credit reports.
However, information furnished by a lender cannot simply be changed because the borrower disagrees with it. The disputed information generally requires verification with the concerned Credit Institution.
This is why documentary consistency matters.
If the lender’s records establish that restructuring actually occurred, the borrower cannot reasonably expect an accurate historical event to disappear merely because the account is now closed.
If the lender’s verified records establish that the restructuring classification was incorrectly furnished, the credit information should reflect the corrected position through the applicable process.
RBI’s credit-information framework also places responsibilities on Credit Institutions and Credit Information Companies regarding the updating and correction of credit information and provides timelines for complaint resolution under applicable conditions.
The purpose of this framework is accuracy of credit information.
It is not a mechanism for converting every adverse but accurate historical event into a favourable classification.
9. Why Should the Documents Be Examined Before Seeking Rectification?
A Credit Report provides the reported information, but it may not tell the complete contractual story of the loan by itself.
Suppose a borrower sees “Restructured” and says:
“I never restructured my loan.”
Before reaching a conclusion, the account documentation should be examined.
Depending on the case, relevant records may include:
- Original sanction letter
- Restructuring letter, approval or agreement, if any
- Revised repayment schedule, if applicable
- Loan account statements
- Repayment history
- Communications concerning modification of the facility
- Closure letter or NOC
- Complete Credit Report
These documents help answer a sequence of important questions:
What were the original loan terms?
Were those terms subsequently modified?
Why were they modified?
Was the modification connected with financial difficulty and a concession by the lender?
Was there a formal restructuring arrangement?
What information did the lender ultimately furnish to the Credit Information Company?
This is why the appropriate professional approach should be:
Verification First → Rectification Second
Without establishing the underlying facts, there is a risk of treating accurate information as an error—or overlooking a genuine reporting discrepancy.
10. Does a Restructured Loan Affect Future Loan Eligibility?
It can be relevant, but it does not automatically mean that a future loan will be rejected.
Banks and other lenders have their own credit policies, underwriting models and risk-appetite frameworks.
A previous restructuring may be one factor considered when evaluating the applicant’s earlier financial stress and repayment history.
But a credit decision is rarely based on one field alone.
Depending on the product and lender, assessment may also consider factors such as:
- Current income or business cash flow
- Existing debt obligations
- Overall repayment behaviour
- Credit exposure and requested loan amount
- Nature of the credit product
- Security or collateral
- Banking conduct
- Recent credit behaviour
- Internal lender policies and risk criteria
Therefore, two extreme statements should be avoided.
“Restructured means your next loan will definitely be rejected.”
This is incorrect.
And:
“The loan is closed, so the restructuring history no longer matters.”
This is also too broad.
The significance of restructuring history depends on the complete credit profile and the prospective lender’s assessment.
No Credit Rectification professional can legitimately guarantee loan approval merely because a particular reporting discrepancy has been corrected.
11. Does Every Bank Treat a Restructured Account Negatively?
No uniform conclusion should be drawn.
Different lenders may apply different internal underwriting standards depending on the credit product, borrower profile, loan amount, risk appetite and other relevant factors.
A restructuring event may receive attention because it can indicate that the original contractual repayment arrangement had to be modified.
However, its significance cannot be evaluated in isolation.
A borrower who successfully serviced a restructured facility and ultimately repaid it may have a different subsequent credit profile from another borrower with continuing repayment difficulties.
Likewise, a secured business facility may be assessed differently from an unsecured consumer loan.
This is why it would be misleading to claim that every lender treats every restructuring event identically.
The Credit Report supplies information.
The prospective lender evaluates that information together with its own underwriting criteria.
12. Why Loan Closure and Credit History Must Be Read Separately
This entire issue becomes easier to understand when we separate two questions.
Question 1: What is the position of the loan today?
The loan may have been completely repaid and closed.
Question 2: What happened during the life of the loan?
The account may—or may not—have undergone restructuring.
These questions can have different answers.
For example:
Original Facility → Restructuring → Revised Repayment → Successful Repayment → Closure
The final closure does not make the earlier restructuring event imaginary.
Conversely:
Original Facility → Normal Repayment/Permitted Contractual Changes → Successful Repayment → Closure
If the lender’s records do not support restructuring but a restructuring classification appears in the Credit Report, the reporting deserves examination.
This is why simply showing a closure letter may not answer every question about the account’s historical reporting.
The complete sequence matters.
Frequently Asked Questions
1. My loan is closed. Why does CIBIL still show Restructured?
Because closure and restructuring can represent different information. Closure concerns the eventual position of the loan, while restructuring may describe an event that occurred earlier during the account’s life.
2. Does Restructured mean I failed to repay the loan?
Not necessarily.
A loan may have been restructured and subsequently repaid successfully under the revised arrangement. The complete repayment history must be examined.
3. Does an EMI have to bounce before a loan can be restructured?
No.
Financial difficulty may exist without an EMI already being overdue. Conversely, an EMI bounce alone does not prove that formal restructuring occurred.
4. If my interest rate changed, does that mean my loan was restructured?
Not automatically.
The reason, contractual framework and circumstances surrounding the modification matter. An ordinary contractual or regulatory rate change should not automatically be treated as proof of restructuring.
5. If I fully repaid the restructured loan, can the restructuring history automatically be removed?
No.
If restructuring genuinely occurred and was accurately reported, subsequent full repayment does not automatically make that historical event inaccurate.
6. What if I never requested or agreed to restructuring?
The underlying records should be examined. The sanction terms, account statements, any restructuring documentation, repayment history, closure records and Credit Report can help establish whether the classification corresponds with the actual account history.
7. Can an incorrect Restructured classification be corrected?
Yes, where the information is established to be inaccurate through the applicable verification and correction framework. Raising a dispute, however, does not itself prove that the information is wrong.
8. Will a Restructured status automatically cause my next loan to be rejected?
No.
A prospective lender may consider restructuring history as one factor, but credit decisions generally involve multiple factors including repayment behaviour, income or cash flow, existing obligations, product type, loan amount, security and internal credit policies.
My Perspective
In my experience, borrowers often look at a closed loan and understandably ask:
“If I have repaid everything, why should Restructured still appear?”
The answer lies in understanding the difference between repayment outcome and credit history.
If restructuring genuinely occurred, successful repayment afterward is important—but it does not mean the restructuring never happened.
At the same time, a borrower should not be expected to accept a restructuring classification that is inconsistent with the lender’s own records.
That is why I believe the correct approach is not to begin with:
“How do we remove Restructured?”
The first question should be:
“Was this loan actually restructured, and does the Credit Report accurately represent what happened?”
Only after answering that question should rectification be considered.
Credit Rectification must be based on accuracy.
It should never be positioned as a method of erasing legitimate credit history merely because that history may influence a future lender’s assessment.
Final Takeaway
If your loan is fully repaid and closed but your CIBIL Report still contains a restructuring-related classification, remember:
Loan Closed ≠ Restructuring Never Happened
A genuine restructuring event may remain relevant to the account’s historical information even after successful repayment.
But:
Restructured Showing ≠ Automatically Correct
If you never underwent restructuring, or if the lender’s own documents do not support the reported classification, the information may require investigation.
And importantly:
EMI Bounce ≠ Proof of Restructuring
Interest Rate Change ≠ Automatically Restructuring
Full Repayment ≠ Automatic Removal of Accurate Historical Information
The right approach is simple:
Verify the account history first. Determine whether rectification is justified second.
Professional Credit Report Assessment & Credit Rectification
Is your loan already closed but your CIBIL Report still showing a restructuring-related classification?
If you are uncertain whether the status corresponds with your sanction terms, repayment history and lender records, the account may require professional examination.
Apoorvaa provides professional Credit Report assessment and Credit Rectification services for individuals and businesses where material credit information requires verification and, where justified, correction.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported information, an increase in any credit score or approval of a future loan application.
Related Credit Education
- Post Write-Off Settled in CIBIL Report After Loan Closure: What Does It Mean?
- Loan Closed but CIBIL Shows Outstanding Balance? Here’s Why
- Old Loan Suddenly Appeared in CIBIL Report After Years? Here’s What It Means
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed