

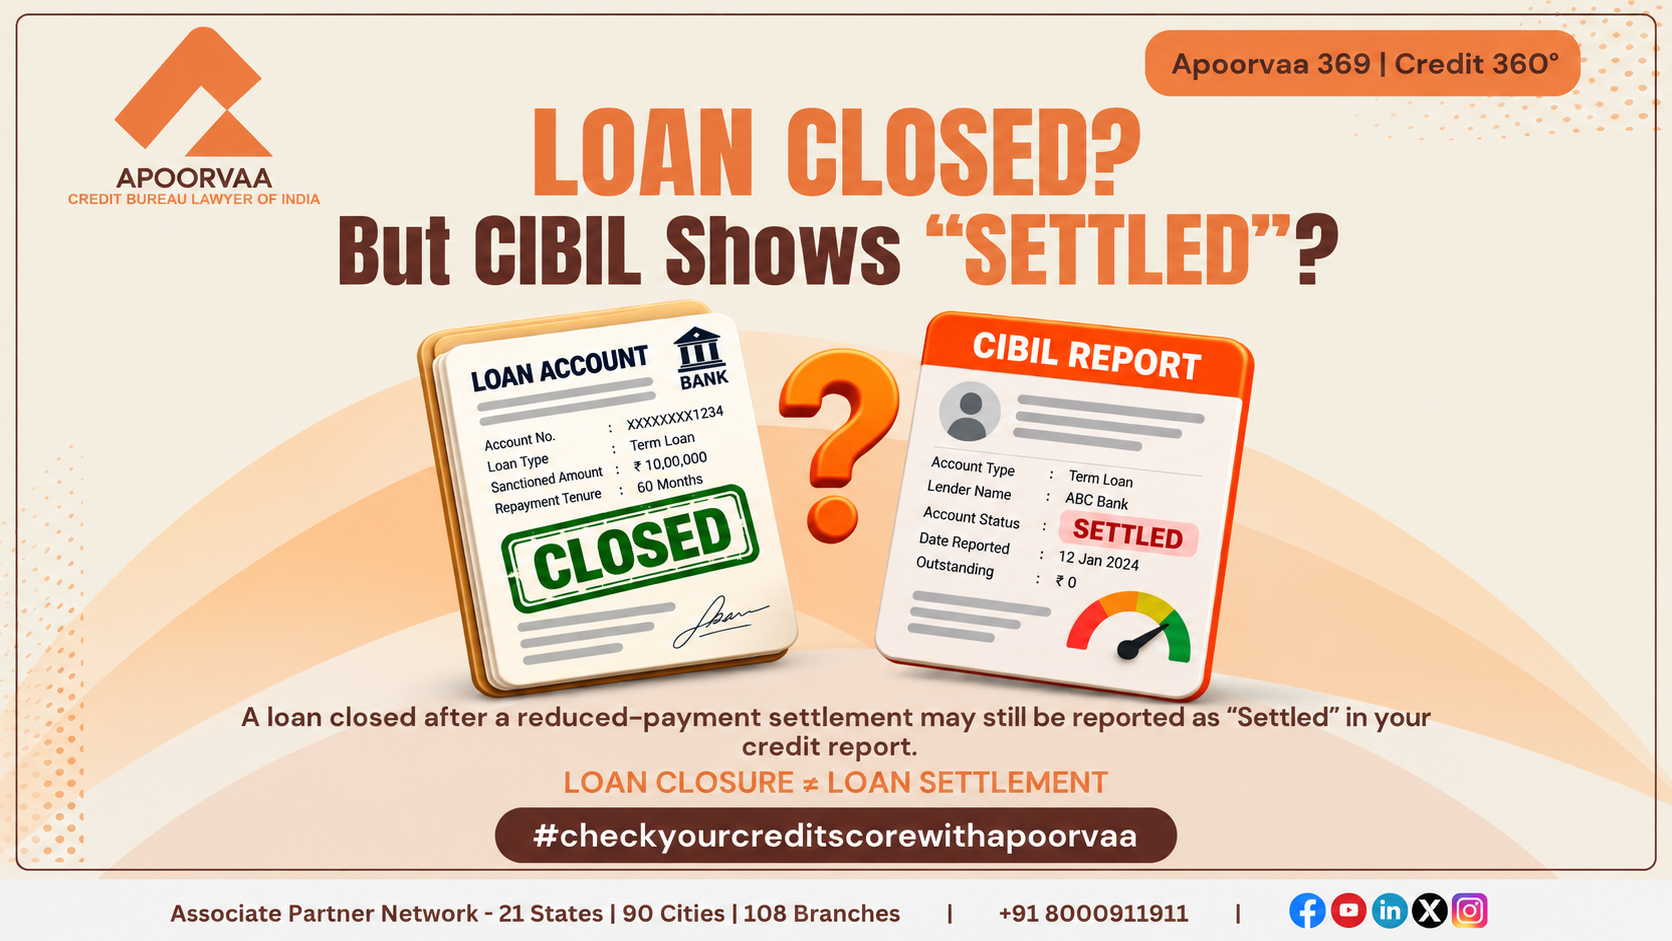
“My loan is closed. Why is CIBIL still showing Settled?”
A YouTube viewer recently raised this question after checking a CIBIL Report.
The viewer explained that the bank had accepted payment and closed the loan account. However, the Credit Report continued to show “Settled.” When the viewer applied for another loan, the application was rejected.
The immediate assumption was that the bank had reported the account incorrectly.
But that is not necessarily the case.
A bank may close a loan account after receiving an agreed settlement amount and still report the account as Settled to a credit bureau.
The reason is that closure of an account and the manner in which the loan was resolved are two different matters.
An account may no longer have an amount payable under an agreed settlement, but that does not automatically mean the borrower repaid the original contractual dues in full.
This distinction is central to understanding why a loan can appear closed in the bank’s records while its credit-bureau status reflects settlement.
TransUnion CIBIL’s official guidance distinguishes a loan repaid in full from one for which the lender accepted a lower settlement amount. CIBIL explains that the latter may be reported as Settled and that lenders may consider this information when assessing a future application.
What Does “Loan Closed” Actually Mean?
In everyday conversation, customers often use the words “loan closed” to mean that they no longer need to make payments to the bank.
However, the expression can describe different circumstances.
A loan may have been closed after the borrower repaid the amount payable according to the contractual terms.
Alternatively, the lender may have accepted a negotiated amount under a settlement arrangement and closed the account after the borrower fulfilled those agreed terms.
The result may look similar to the customer: the bank is no longer asking for further payment under the completed arrangement.
But the repayment history behind those outcomes is different.
Example: Closure Through Full Contractual Repayment
A borrower takes a loan and repays the amounts payable under the loan agreement, including applicable interest and other legitimate dues.
The lender then closes the facility.
In this situation, the account has been resolved through repayment of the contractual obligation.
Example: Closure Following a Settlement
A borrower experiences repayment difficulties and is unable to discharge the amount payable.
The borrower and lender subsequently agree to resolve the account through payment of a negotiated settlement amount.
After receiving the agreed payment and fulfilment of the settlement terms, the bank closes the account.
However, the account may still be classified as Settled in the Credit Report because the lender resolved its claim through a settlement arrangement rather than ordinary full contractual repayment.
Both accounts may be closed, but they did not reach closure in the same way.
Closed vs Settled in CIBIL: What Is the Difference?
The distinction is easier to understand when the two concepts are considered separately.
| Particulars | Closed | Settled |
| Basic meaning | The loan facility has been closed following repayment or another applicable resolution | The lender has reported that the account was resolved through a settlement arrangement |
| Repayment position | In an ordinary fully repaid closure, the contractual amount payable has been discharged | The lender may have accepted a negotiated amount to resolve its claims |
| Does the account remain active? | Not necessarily; it has been closed | It may also be closed after the settlement terms are fulfilled |
| What does the status communicate? | The account’s closure position | The manner in which the lender resolved the account |
| Future lending relevance | Considered with the complete credit history | May raise questions about the earlier repayment history |
A borrower should not assume that the bank’s use of the word “closed” in an account statement or closure communication necessarily determines how the loan must be classified in the CIBIL Report.
The actual repayment circumstances matter.
“Closed” can describe the account’s present position. “Settled” can describe how the account reached that position.
Can a Loan Be Closed and Settled at the Same Time?
Yes. A loan can be closed following a completed settlement while the Credit Report continues to reflect its settlement classification.
This is the central answer to the YouTube viewer’s question.
Suppose a borrower has an outstanding amount of ₹2 lakh under a loan account.
Because of financial difficulties, the borrower and lender agree to resolve the account through payment of ₹1.5 lakh under a compromise settlement.
The borrower pays the agreed amount and fulfils the settlement terms.
The bank may then close the account in accordance with that arrangement.
From the customer’s perspective, the loan is closed.
However, the lender may report the account as Settled because the resolution involved an agreed settlement rather than ordinary repayment of the full contractual dues.
The bank’s closure of the account and its reporting of the settlement are therefore not inherently contradictory.
The RBI’s Framework for Compromise Settlements and Technical Write-offs, dated 8 June 2023, defines a compromise settlement as a negotiated arrangement to settle a regulated entity’s claims in cash. Such an arrangement may involve the lender sacrificing part of the amount due and waiving its claim to that extent.
The important question is not merely whether the account is closed. It is how the account was resolved.
What Is the Role of OTS in Loan Closure?
OTS stands for One-Time Settlement.
In the context of a negotiated loan resolution, the lender and borrower may agree on an amount and terms for settling the lender’s claims.
A borrower may enter into such an arrangement because they cannot repay the full amount otherwise payable.
Once the borrower fulfils the agreed terms, the lender may treat the account as resolved under that settlement.
However, the completion of an OTS does not automatically mean that the account must be reported as an ordinary fully repaid loan.
This is where borrower expectations and credit-bureau reporting can differ.
The borrower may think:
“I paid exactly what the bank asked me to pay under the OTS. Therefore, my account should show Closed, not Settled.”
But the lender may have accepted that payment specifically as a negotiated resolution involving a reduction of its claim.
The payment may fully satisfy the settlement agreement without representing full repayment of the original contractual amount.
Those are different propositions.
Does Every Waiver of Interest or Penalty Automatically Mean Settlement?
No.
This distinction must be handled carefully.
A customer may receive an adjustment, reversal or waiver of a particular charge without necessarily entering into a compromise settlement of the loan.
For example, a lender may reverse an incorrectly applied fee or make another account adjustment.
That event alone does not establish that the entire loan was settled for less than the amount legitimately payable.
Similarly, the word “waiver” in a communication should not be interpreted without understanding what was waived, why it was waived and the terms under which the account was resolved.
The relevant questions are whether there was a negotiated settlement of the lender’s claim, what the borrower was contractually required to pay, and how the lender actually resolved and reported the account.
It would be inaccurate to state that every interest concession, penalty reversal or fee adjustment automatically requires a Settled classification.
Does Zero Outstanding Mean the Settlement Status Must Disappear?
No. A zero current balance does not automatically mean that a historical settlement classification must disappear.
This is another common source of confusion.
A customer may see the following information:
Current Balance: ₹0
Amount Overdue: ₹0
Account Status: Settled
The customer may ask:
“If I owe nothing now, why is the account still showing Settled?”
The answer is that these fields can communicate different information.
A zero current balance may indicate that no balance is presently being reported against the account.
The Settled status may communicate that the account was resolved through a settlement arrangement.
There is no necessary contradiction between those two facts.
Zero outstanding and full contractual repayment are not interchangeable concepts.
For example, a lender may have agreed to accept a reduced amount in full settlement of its claims.
Once the agreed terms are fulfilled, the current balance may be reported as zero while the historical settlement classification remains relevant.
A borrower should therefore avoid interpreting the current balance without understanding the account’s repayment and resolution history.
Does a Loan Closure Letter Prove That Settled Status Is Incorrect?
Not automatically.
A borrower may possess a letter stating that the loan account has been closed or that the lender has no further claim under a completed arrangement.
That document may be important evidence of the account’s present position.
However, the meaning of the letter depends on its wording and the circumstances in which it was issued.
For example, a closure letter following full contractual repayment is not necessarily equivalent to a closure communication issued after a negotiated settlement.
A letter confirming that a settlement has been completed may establish that the borrower fulfilled the settlement terms.
It does not necessarily establish that no settlement occurred.
Similarly, a no-dues or no-objection communication should be interpreted in light of the underlying account records and any agreement between the parties.
The existence of a closure document does not, by itself, prove that a Settled classification is inaccurate.
The actual repayment and closure circumstances must be examined.
Loan Closure, Settlement and Write-Off Are Different Events
Because these expressions often appear in discussions about adverse credit history, they should not be confused.
Ordinary loan closure may follow repayment of the amount payable under the loan agreement.
Loan settlement involves resolving the lender’s claims according to an agreed arrangement, potentially involving a reduction in the amount otherwise due.
Technical write-off is a separate accounting treatment.
Under RBI’s framework, a technical write-off does not itself waive the lender’s claim against the borrower. A compromise settlement, by contrast, may involve an agreed sacrifice of the amount due and a corresponding waiver of the lender’s claim to that extent.
A customer may encounter more than one of these events during the history of a stressed loan.
That is why a single word in the CIBIL Report should not be used to reconstruct the entire account history.
Why Does CIBIL Show Settled Even After the Bank Has Closed the Loan?
A customer may have fulfilled every condition mentioned in a One-Time Settlement (OTS) letter.
The bank may have accepted the agreed amount, stopped demanding further payment under that arrangement and confirmed that the account has been closed.
Yet the CIBIL Report may continue to display Settled.
The reason is that the closure of an account and the historical manner of its resolution are separate matters.
If the lender accepted a negotiated amount in satisfaction of its claims, the completion of that arrangement does not necessarily convert the earlier settlement into ordinary full contractual repayment.
Consider two borrowers.
Borrower A repays the amount payable under the loan agreement, including applicable interest and legitimate charges.
Borrower B experiences repayment difficulties and enters into an OTS under which the lender accepts a negotiated amount to resolve its claims.
Both borrowers may eventually have closed accounts with no further amount payable under their respective arrangements.
However, the circumstances leading to closure are different.
A closed account does not automatically establish that the loan was repaid through ordinary full contractual repayment.
This distinction becomes particularly important when the borrower applies for another loan.
Can Settled Status Affect Future Loan Approval?
Yes. A Settled account may be relevant to a lender’s assessment of a fresh loan application.
A prospective lender may review the borrower’s complete credit history to understand how earlier obligations were managed.
Where an account was resolved through a compromise settlement, the lender may consider that information alongside other aspects of the borrower’s credit profile.
TransUnion CIBIL explains that a Settled status can affect how lenders evaluate credit applications because it distinguishes a settlement from repayment of the full amount due.
However, it would be incorrect to state that every bank must automatically reject every borrower whose Credit Report contains a Settled account.
A lending decision may also involve:
- The borrower’s subsequent repayment history.
- Current outstanding obligations.
- Income and repayment capacity.
- The type and amount of credit requested.
- The lender’s internal eligibility and credit-risk policies.
A Settled entry may therefore be an important consideration without being the sole explanation for every loan rejection.
Why does this matter for the borrower?
A customer may focus on the fact that the earlier account is no longer active.
The new lender may focus on how that account was resolved.
These are different perspectives on the same credit facility.
Does RBI Prescribe a Cooling Period After Loan Settlement?
RBI’s Framework for Compromise Settlements and Technical Write-offs, dated 8 June 2023, contains provisions concerning fresh exposure to borrowers who have undergone compromise settlements.
Under the framework, regulated entities must determine a cooling period through their Board-approved policies before assuming fresh exposures to such borrowers.
For exposures other than farm credit, the framework specifies a minimum cooling period of 12 months. Regulated entities may prescribe a longer period under their policies. The cooling period for farm credit exposures is determined according to the respective Board-approved policies.
This regulatory requirement should not be confused with a promise that a borrower will become eligible for a new loan immediately after the applicable period ends.
A cooling period and a lender’s overall credit assessment are separate matters.
Completion of a settlement does not guarantee approval of the next loan application.
Does Zero Outstanding Mean the Settlement Status Must Disappear?
No. Zero outstanding and historical settlement information communicate different things.
Suppose the CIBIL Report shows:
| Account Information | Reported Position |
| Current Balance | ₹0 |
| Amount Overdue | ₹0 |
| Account Status | Settled |
The borrower may assume that the three fields are inconsistent.
But they are not necessarily contradictory.
The zero balance may reflect the account’s present financial position following completion of the agreed arrangement.
The Settled classification may reflect the manner in which the lender resolved the earlier obligation.
A customer who has fulfilled a compromise settlement may therefore have no further amount payable under that arrangement while the Credit Report continues to reflect the settlement history.
The important distinction
Current Balance answers a question about the reported balance.
Settled Status answers a question about the account’s reported resolution history.
One should not automatically be used to invalidate the other.
What If I Pay the Remaining Amount After a Loan Settlement?
Another customer may ask:
“My loan was settled earlier. If I now pay the remaining amount, will CIBIL change Settled to Closed?”
There is no universal answer.
A subsequent payment may be relevant to the account’s present position. However, its effect on the reported classification depends on the actual account records, the lender’s agreement and the circumstances of the payment.
For example, the borrower may make an additional payment after an earlier settlement.
That does not automatically establish that the original settlement never occurred.
Likewise, a customer should not assume that a further payment guarantees removal of accurately reported historical settlement information.
The relevant questions include:
What was the original contractual liability?
What amount did the lender agree to accept under the settlement?
What was subsequently paid?
How did the lender treat the additional payment?
Does the current Credit Report accurately reflect the account’s actual position?
A professional assessment must distinguish a genuine reporting discrepancy from a request to erase accurate adverse credit history.
Does a No-Dues Certificate Mean CIBIL Must Show Closed Instead of Settled?
Not automatically.
A customer may possess a No-Dues Certificate, No-Objection Certificate or loan closure letter and believe that the Settled status must therefore be incorrect.
These documents can be important evidence of the account’s resolution.
However, their meaning depends on the wording and the circumstances in which they were issued.
A document confirming that the borrower fulfilled an OTS may establish that the settlement was completed.
It does not necessarily establish that the original contractual dues were repaid in full.
Similarly, a closure letter issued after ordinary full repayment may support a different interpretation.
The document must be read alongside the loan agreement, repayment history and any settlement arrangement.
The title of a document alone does not determine the correct credit-bureau classification.
When Is Settled Status in CIBIL Actually Incorrect?
This is where the discussion moves from loan settlement education to Credit Rectification.
A borrower may have a genuine concern when the reported classification does not appear consistent with what actually happened to the loan account.
However, an adverse status is not automatically an inaccurate status.
Consider the following situations.
Situation 1: The Borrower Fully Repaid the Contractual Dues
The borrower repaid the amount legitimately payable under the loan agreement.
There was no compromise settlement involving a reduction of the lender’s claim.
However, the CIBIL Report shows Settled.
In this situation, the reported classification may require examination against the actual account records.
Situation 2: The Borrower Completed an OTS
The lender agreed to accept a negotiated amount in resolution of its claims.
The borrower fulfilled the agreed terms.
The bank closed the account, and CIBIL shows Settled.
The mere fact that the account is closed does not establish that the classification is wrong.
Situation 3: The Current Balance Does Not Reflect the Completed Arrangement
The borrower fulfilled the settlement terms, but the Credit Report continues to show a balance that appears inconsistent with the lender’s records.
The concern may relate to the current balance or other account information rather than the historical settlement classification.
Situation 4: A Charge Was Reversed, but No Compromise Settlement Occurred
The lender reversed an incorrectly applied fee or made another adjustment, and the borrower discharged the amount legitimately payable.
The customer later discovers a Settled classification.
The reporting requires examination of the actual contractual liability, adjustment and account-resolution circumstances.
Not every interest concession, penalty waiver or fee reversal automatically establishes that the loan was settled.
Situation 5: The Report Has Not Reflected a Recent Account Development
The customer recently repaid or resolved the account.
The CIBIL Report has not yet reflected the subsequent information.
The reporting date and actual account developments become relevant.
TransUnion CIBIL’s official guidance explains that credit institutions submit account information and that recent payments may not immediately appear in the report. It also states that CIBIL cannot independently modify lender-reported account information without confirmation from the relevant credit institution.
The central question is not whether Settled is an unfavourable status.
It is whether Settled accurately describes the way the account was resolved.
Correctly Reported Settlement vs Inaccurate Credit Information
This distinction should guide every discussion about settlement-related Credit Rectification.
| Account Circumstance | Relevant Question |
| Genuine OTS completed | Does the report accurately reflect the settlement and present account position? |
| Full contractual repayment | Why is the account classified as Settled? |
| Additional payment after settlement | What changed in the account, and how was that change recorded? |
| Zero current balance with Settled status | Is the zero balance consistent with a completed settlement? |
| Outstanding balance inconsistent with records | Does the reported balance accurately reflect the actual account position? |
| Recent account closure | Has the lender’s subsequent reporting been reflected? |
A customer should not assume that every Settled account can be converted into Closed merely because the settlement payment has been completed.
Equally, a lender’s classification should not be treated as unquestionably accurate where the underlying records suggest otherwise.
The correct reporting outcome depends on the facts of the particular account.
Why Professional Credit Report Review Matters
A customer may approach a professional with a straightforward request:
“My loan is closed. Please remove Settled from my CIBIL Report.”
However, responsible Credit Rectification begins with understanding what the customer means by “closed.”
Was the loan repaid according to the contractual terms?
Was an OTS accepted?
Was there a waiver or reversal of a particular charge?
Was the account subsequently resolved through another arrangement?
Does the reported current balance reflect the actual position?
These questions matter because two customers with apparently similar CIBIL Reports may have materially different account histories.
One may have accurately reported settlement information.
Another may have a genuine discrepancy requiring attention.
The purpose of professional Credit Report review is to identify that distinction.
Credit Rectification should address inaccurate, inconsistent or outdated information—not promise deletion of every correctly reported settlement.
Frequently Asked Questions
1. My loan is closed. Why does CIBIL still show Settled?
The lender may have closed the account after receiving an agreed settlement amount. The Settled status may reflect how the account was resolved rather than whether it remains active.
2. Can a loan be closed and settled at the same time?
Yes. An account may be closed after the borrower fulfils a settlement arrangement while the Credit Report continues to reflect the settlement classification.
3. Does zero outstanding mean the account must show Closed?
No. A zero current balance does not automatically establish that the original contractual dues were repaid in full.
4. Does an OTS always mean the loan remains active?
No. The lender may close the account after the borrower fulfils the settlement terms. The credit-bureau classification is a separate matter.
5. Does every penalty waiver make a loan Settled?
No. The underlying contractual liability, reason for the adjustment and actual account-resolution arrangement matter.
6. Can Settled status affect another loan application?
Yes. A lender may consider settlement history during credit assessment, but the status does not establish automatic rejection by every lender.
7. Will paying more money after settlement automatically remove Settled?
No. A subsequent payment does not guarantee deletion of accurately reported settlement history.
8. Is a No-Dues Certificate enough to prove that Settled is incorrect?
Not necessarily. The document must be understood in the context of the underlying repayment or settlement arrangement.
9. Can an incorrectly reported Settled status be corrected?
A genuinely inaccurate classification may require correction. The appropriate reporting outcome depends on the lender’s records and actual account circumstances.
10. Should I apply for another loan immediately after completing an OTS?
The applicable RBI framework, the lender’s policy and the borrower’s complete credit profile may all be relevant. Completion of an OTS does not guarantee eligibility or approval.
My Perspective: Loan Closure Is Not the End of the Credit-Reporting Question
When a customer says:
“Sir, my loan is closed, but CIBIL still shows Settled,”
I do not consider the word “closed” alone sufficient to determine whether the Credit Report is incorrect.
The important issue is how the loan reached closure.
A borrower who repaid the contractual dues and a borrower who fulfilled a negotiated settlement may both have closed accounts.
But the repayment circumstances are different.
The customer should also understand that a zero current balance does not automatically erase historical settlement information.
At the same time, a genuine reporting discrepancy should not be ignored merely because the account once experienced repayment difficulties.
My approach is to distinguish three questions:
Was the account actually settled?
Does the present Credit Report accurately reflect the account’s subsequent developments?
Is there a genuine reporting concern that requires professional Credit Rectification?
The objective is not simply to change an unfavourable word.
It is to understand whether the Credit Report accurately represents the loan account.
Final Takeaway
A loan can be closed while CIBIL continues to show Settled.
That is not necessarily a reporting error.
A bank may close the account after the borrower fulfils an agreed OTS while continuing to report that the loan was resolved through settlement.
Similarly, zero outstanding does not automatically mean that the original contractual dues were repaid in full.
However, where the reported classification, balance or other account information appears inconsistent with the actual records, the concern deserves closer examination.
Before applying for another loan, understand not only whether your previous account is closed—but also how that closure is reflected in your complete Credit Report.
Professional Credit Report Assessment
Is your loan closed, but your CIBIL Report still shows Settled?
The presence of Settled does not automatically establish a reporting error. However, if the classification, outstanding balance or other account information does not appear consistent with the actual repayment and closure circumstances, professional review may help identify a genuine Credit Rectification concern.
Apoorvaa – Credit Bureau Lawyer of India provides professional Credit Report assessment and Credit Rectification services for individuals and businesses.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported settlement history, a particular CIBIL Score or approval of a new loan.
Related Credit Education — Internal Links
- Loan Settlement and CIBIL: Why You Should Think Before Settling
- Write-Off in CIBIL Report: Does It Mean Your Loan Is Waived?
- Suit Filed in CIBIL Report: What Does It Mean and Why Can It Still Show After Loan Repayment?
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India and works in the field of Credit Rectification, Credit Report analysis and credit-related borrower guidance.
Advocate Apurva Bhagat focuses on credit-bureau law, and helping individuals and businesses understand the distinction between contractual loan obligations, lender-reported account status and genuine credit-reporting discrepancies.

Comments are closed