

“Sir, please correct my CIBIL for just two months. Once my loan is approved, the old problems can come back.”
This is a request we increasingly encounter from borrowers who are facing difficulties obtaining personal loans, business finance or working capital renewals.
Some borrowers also tell us that third-party agents have promised to temporarily remove overdue amounts, write-offs or other adverse information from their credit reports.
The promise sounds convenient: obtain a clean credit report, secure the loan and allow the old information to return later.
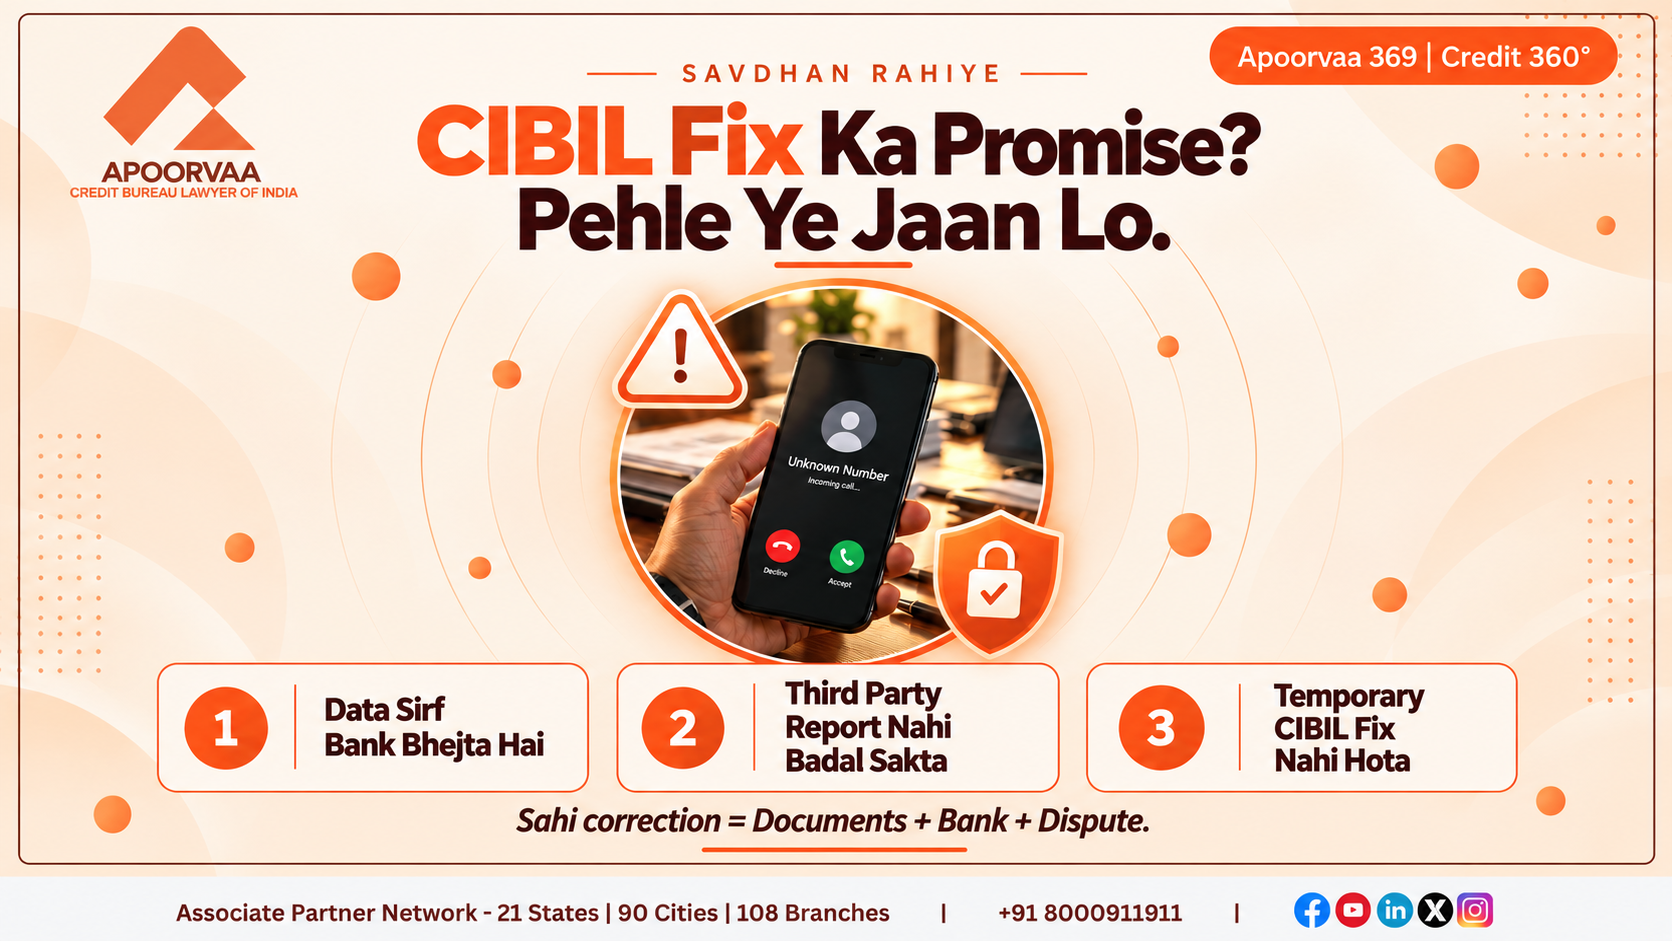
However, there is no recognised credit-bureau rectification procedure designed to temporarily suppress accurate adverse information for a fixed period simply to facilitate loan approval.
Such claims require serious scrutiny because they may involve misleading representations, financial exploitation or unauthorised manipulation of documents.
1. What Is Temporary CIBIL Rectification?
Temporary CIBIL Rectification is a phrase sometimes used by intermediaries to describe a supposed arrangement under which adverse credit information is removed for a limited period, often 30 or 60 days.
The borrower is told that the information will reappear after the loan is sanctioned.
This is fundamentally different from legitimate credit report correction.
A genuine rectification process addresses information that is inaccurate, incomplete, outdated or otherwise requires correction based on verified records.
For example, an account may incorrectly show an overdue balance despite repayment, or a loan may be associated with the wrong borrower.
Such matters can be examined through the applicable credit-information dispute and correction process.
But where a lender has accurately reported an outstanding default, the information cannot legitimately be removed merely because it is affecting the borrower’s loan eligibility.
The purpose of rectification is accuracy, not the temporary concealment of genuine credit history.
2. How Credit Bureau Reporting Actually Works in India
India’s credit information framework is governed principally by the Credit Information Companies (Regulation) Act, 2005, associated rules and regulations, and applicable Reserve Bank of India directions.
Credit Information Companies, including TransUnion CIBIL, Experian, Equifax and CRIF High Mark, maintain credit information received from authorised credit institutions.
Banks and other regulated credit institutions furnish information relating to their borrowers and credit facilities in accordance with applicable requirements.
Credit bureaus process this information and make credit reports available to authorised users for permitted purposes.
Can a Third-Party Agent Directly Change CIBIL Data?
An independent agent does not have legitimate authority to alter a lender’s underlying loan records or independently rewrite credit information held by a bureau.
A borrower or authorised representative may assist with a dispute, but a correction must follow the applicable verification and reporting framework.
Where information is inaccurate, the relevant credit institution and credit information company have responsibilities under the governing framework.
This is why a promise to change credit information without any supporting records or verification should raise immediate concern.
3. Why Two-Month CIBIL Correction Promises Are Misleading
Consider a borrower whose credit report accurately reflects a loan default.
A third party claims that the default can be removed for 60 days, allowing the borrower to apply for a new loan.
The agent further promises that the old default will automatically return after the loan is approved.
There is no official credit-bureau facility that authorises this arrangement.
A credit report may change over time because lenders submit updated information, corrections are processed or new account developments occur.
However, normal reporting updates should not be confused with a legitimate service for temporarily concealing accurate adverse information.
If an intermediary knowingly misrepresents their authority, fabricates documents or manipulates information to obtain money or influence lending decisions, the conduct may raise legal concerns depending on the facts and evidence.
Not every inaccurate promise automatically establishes a criminal offence. Any allegation of fraud or cheating must be assessed on the actual conduct and applicable law.
4. Why Borrowers Become Vulnerable to Such Offers
Borrowers often encounter these promises when they urgently need finance.
A business owner may be waiting for a cash credit renewal.
An MSME may require additional working capital to fulfil orders.
An individual may be trying to obtain a home loan or transfer an existing loan.
When an adverse credit entry becomes an obstacle, the possibility of a temporary clean report can appear attractive.
Some intermediaries exploit this urgency by demanding advance fees or claiming special access to credit bureaus.
Borrowers should be especially cautious when an agent guarantees a clean report without reviewing the underlying loan records.
A legitimate credit-reporting concern requires evidence and verification, not an assurance that adverse information can disappear for a predetermined period.
5. Can Corrected Credit Information Reappear Later?
Yes. A previously corrected entry may sometimes reappear in a subsequent credit report.
However, this does not prove that a two-month rectification facility exists.
A reappearing entry may result from a subsequent lender submission, inconsistent reporting, an unresolved data mismatch or another reporting issue.
The correct response is to examine the updated information, compare it with supporting records and seek appropriate verification where an error remains.
A genuine reporting discrepancy that recurs is different from an arrangement to remove accurate information temporarily.
The key question is whether the reported information accurately reflects the borrower’s underlying credit obligations.
6. Genuine Credit Report Correction vs Temporary Manipulation
The most important distinction is between correcting inaccurate information and concealing accurate information.
If a credit report incorrectly shows an overdue amount, wrong account ownership, inaccurate repayment status or another reporting discrepancy, the borrower may seek verification and correction.
However, if a loan default, write-off or settlement has been accurately reported, its adverse nature alone does not make it an error.
A genuine correction must have a factual and documentary basis.
A promise to temporarily remove accurate adverse information solely to obtain loan approval is not legitimate credit rectification.
7. Warning Signs of Misleading CIBIL Rectification Offers
Borrowers should exercise caution when an intermediary makes claims such as:
- “We can clear your CIBIL for exactly 60 days.”
- “Your old default will return after your loan is sanctioned.”
- “We can remove any write-off without lender verification.”
- “Pay an advance fee and your loan approval is guaranteed.”
- “We have special access to change credit bureau records.”
These statements are warning signs, particularly when the intermediary refuses to explain the documentary basis of the proposed correction.
Borrowers should not share sensitive documents, passwords or verification codes with unverified agents.
They should also preserve messages, payment records and other evidence if they suspect deception.
8. Can Temporary Credit Manipulation Have Legal Consequences?
Knowingly submitting forged documents, making deceptive representations or manipulating information to influence a lending decision may attract legal consequences under applicable Indian law.
The precise consequences depend on the conduct, evidence and relevant legal provisions.
It is important to distinguish an unsuccessful credit correction request from deliberate fraud.
A genuine reporting error, even if it reappears, does not automatically establish fraudulent conduct.
Similarly, a misleading promise requires factual examination before any person can be accused of a criminal offence.
Where there is credible evidence of deception or document manipulation, affected borrowers may approach the appropriate authorities.
9. What Should Borrowers Do Instead?
Before trusting a credit rectification promise, borrowers should establish whether the disputed information is genuinely incorrect.
The relevant loan documents, repayment records, lender communications and updated credit report can help establish the factual position.
Where an error exists, it should be raised through the appropriate credit institution and credit bureau dispute-resolution process.
If incorrect information reappears after correction, the matter may require renewed verification.
Borrowers should also understand that a corrected credit report does not guarantee a higher CIBIL Score or loan approval. Lending decisions remain subject to the lender’s assessment and policies.
My Professional Recommendation
In my experience, financial urgency often makes borrowers vulnerable to unrealistic credit rectification promises.
Whether the requirement is a personal loan, business loan, balance transfer or working capital renewal, the underlying credit information should be accurate and verifiable.
No borrower should rely on a promise that genuine adverse information can be hidden for two months and restored after financing is obtained.
If someone offers such an arrangement, request a clear explanation of the proposed correction and its supporting records.
If the offer appears deceptive, avoid making payments and preserve the available evidence.
Conclusion
Temporary CIBIL Rectification, presented as a method of hiding genuine defaults for a fixed period, is not a recognised credit-bureau correction facility.
Legitimate rectification exists to address inaccurate, incomplete or outdated credit information through proper verification.
Borrowers must distinguish between an actual reporting error and an accurate but unfavourable credit history.
Credit reporting should reflect verified financial information, not temporary arrangements designed to influence lending decisions.
Accurate credit information is the objective. Temporary manipulation is not the solution.
Need Professional Guidance on Credit Report Discrepancies?
If you are facing an incorrect credit report entry or have received a suspicious offer for temporary CIBIL correction, Apoorvaa can help you understand the reported information and identify matters requiring verification.
Get your personal and Company Credit Reports professionally analysed by Apoorvaa.
For information and guidance, contact our helpline.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Related Credit Education
- Director’s CIBIL Is Poor: Will the Company’s CIBIL Rank Be Affected?
- Wrong Mobile Number or Address in CIBIL Report: Is It Fraud?
- CIBIL Score Dropped After Personal Loan Closure? Here’s Why
About the Author
Advocate Apurva Bhagat is the Founder of Apoorvaa – Credit Bureau Lawyer of India. Through his articles and educational initiatives, he helps borrowers understand credit reports, banking practices, and informed financial decision-making. His objective is to promote financial awareness through practical and responsible guidance.

Comments are closed